


As a business owner, Seamless ACH has helped to significantly reduce the number of checks we have to put in the mail, which has saved us on postage and time spent.

Simple, reliable payment processing built for business owners — including high-risk, high-growth, and subscription-driven brands. No surprises. No shutdowns. No stress.
Accept credit cards and ACH — plus instant payouts — with dedicated support that treats your business like it matters.




• Fast Approvals
• Increase authorization rates—even for hard-to-place merchants
• Reduce risk and disputes with built-in fraud and chargeback support
• Scale with confidence: no surprise holds and flexible reserve options


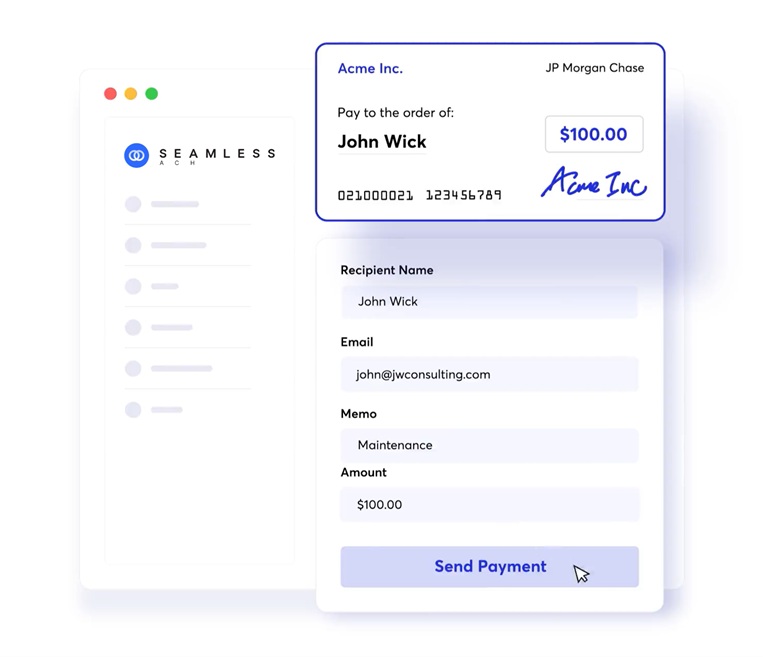
• Accept Pay by Bank at checkout
• Send instant payouts to customers, partners, or vendors
• Improve satisfaction with faster access to funds
• Reduce fraud and returns with Plaid-verified bank transfers
• Stop waiting days for ACH funds to clear
Get approved fast - scale with confidence. Find the right solution for you:
As a business owner, Seamless ACH has helped to significantly reduce the number of checks we have to put in the mail, which has saved us on postage and time spent.
Seamless Merchant has been a great asset to our organization for the past 5 years. They are always quick to respond and a pleasure to work with.
Seamless Merchant has been great at keeping our payment processing fees at an absolute minimum.
Thanks to the insightful advice and great service offered by the team at Seamless Merchant, our ecommerce business operates more efficiently.
eCheck verification has reduced returned checks for our clients by 63% resulting in thousands saved on bank fees. They also offer A+ developer support!
Very reliable verification and great customer service. Customer Support is always responsive and available.
We have over 90 locations and Seamless Chex helps us collect out money faster, easier and more efficiently.
Excellent service! Sending invoices with Seamless ACH has significantly reduced A/R by letting our customers pay online.
SeamlessChex helped us solve one of the crucial problems we were having as a business: recurring payment to vendors.
Seamless ACH allows us to easily request one time and recurring rent payments from our tenants.
SeamlessChex has made it easy for our business to receive funds the next day from our clients.
Every small business needs Seamless ACH! Seamless ACH's allowed me to send and receive payments quickly, securely, and reliably.
SeamlessChex has been an invaluable addition to our company. It has drastically reduced the time to receive.
SeamlessChex is a payment processing company founded in 2012 by Evan and Jonathan Albert. We help businesses accept and send payments by credit card, debit card, ACH, and eCheck — including high-risk, high-growth, and subscription businesses that mainstream processors often decline.
Credit and debit cards (including Apple Pay and Google Pay), ACH bank transfers, eChecks, and Plaid-verified Pay by Bank payments. Most merchants combine card acceptance with bank-debit rails to lower fees and chargeback exposure.
Pricing depends on your industry and risk profile. Card processing for high-risk merchants typically runs 2.95%–5.5%, while ACH and eCheck usually cost under 2% — which is why high-ticket and high-risk merchants route larger payments over bank rails. There are no long-term contracts or hidden fees.
Standard accounts are typically approved the same day. High-risk merchant accounts usually take 72 hours to a few business days depending on the vertical and your documentation, with full processing live within one to two weeks for the hardest-to-place industries.
We serve 60+ industries, including many that mainstream processors reject: nutraceuticals and supplements, peptides, CBD, telemedicine, online gaming, credit repair, debt collection, and high-ticket B2B. See all industries or our Deep Dive guides for vertical-specific detail.
Yes. A previous termination by Stripe, PayPal, or Square does not disqualify you — we underwrite your business on its current merits and have approved many merchants other processors dropped. We also work with businesses on the TMF/MATCH list.
Insights & updates
Practical insights on payments, risk, and industry trends to keep you informed on what’s changing across the payments landscape.
Card processors that only run payments fall under HIPAA's Section 1179 exemption. Learn when one becomes a business associate and how to keep checkout PHI-free.
Continue reading ›
Established nutra card merchants can work a rolling reserve down within a year. See which dispute lines and monthly records back a request for a smaller hold.
Continue reading ›
Cards stay the main way US players fund iGaming accounts through 2028, while pay-by-bank on FedNow and RTP wins payouts first. See what to plan for now.
Continue reading ›Go deeper
In-depth guides that break down complex payment challenges with research, context, and practical guidance.
A 90-day closure notice is a real runway. Move recurring billing to a new credit card merchant account, transfer stored cards, and keep renewals running.
Continue reading ›
Comparing high-risk merchant account providers? Learn which fee lines reach the statement but not the quote, and why markup and reserves often cost more.
Continue reading ›
A nutraceutical merchant account approved in a day can still fail by month 6. Learn what underwriters review and how VAMP pressure changes supplement risk.
Continue reading ›