


Quick Answer
Processors underwrite a 90-day vault as deferred delivery: the customer pays today, and the pulled cards ship later. That puts it closer to travel or pre-order accounts than to card-present retail.
The underwriter is pricing prepaid credit, a randomized outcome, and delayed fulfillment. Not cardboard. Plan for portability, too. Practitioners in a June 2026 payments forum thread advised that "processor migration and token migration need to be planned together," so stored cards can follow you if terms change.
Key Points
- SeamlessChex's underwriting team says processors price five things on vaulted rip platforms: prepaid credit, a randomized outcome, delayed physical fulfillment, stored balances, and buybacks.
- SeamlessChex works with established businesses processing at least $25,000 per month and underwrites vaulted platforms as deferred delivery, closer to travel or pre-order accounts.
- A June 2026 r/PaymentProcessing thread warned that merchants who switch processors without planning the token migration can end up "stuck in limbo for months."
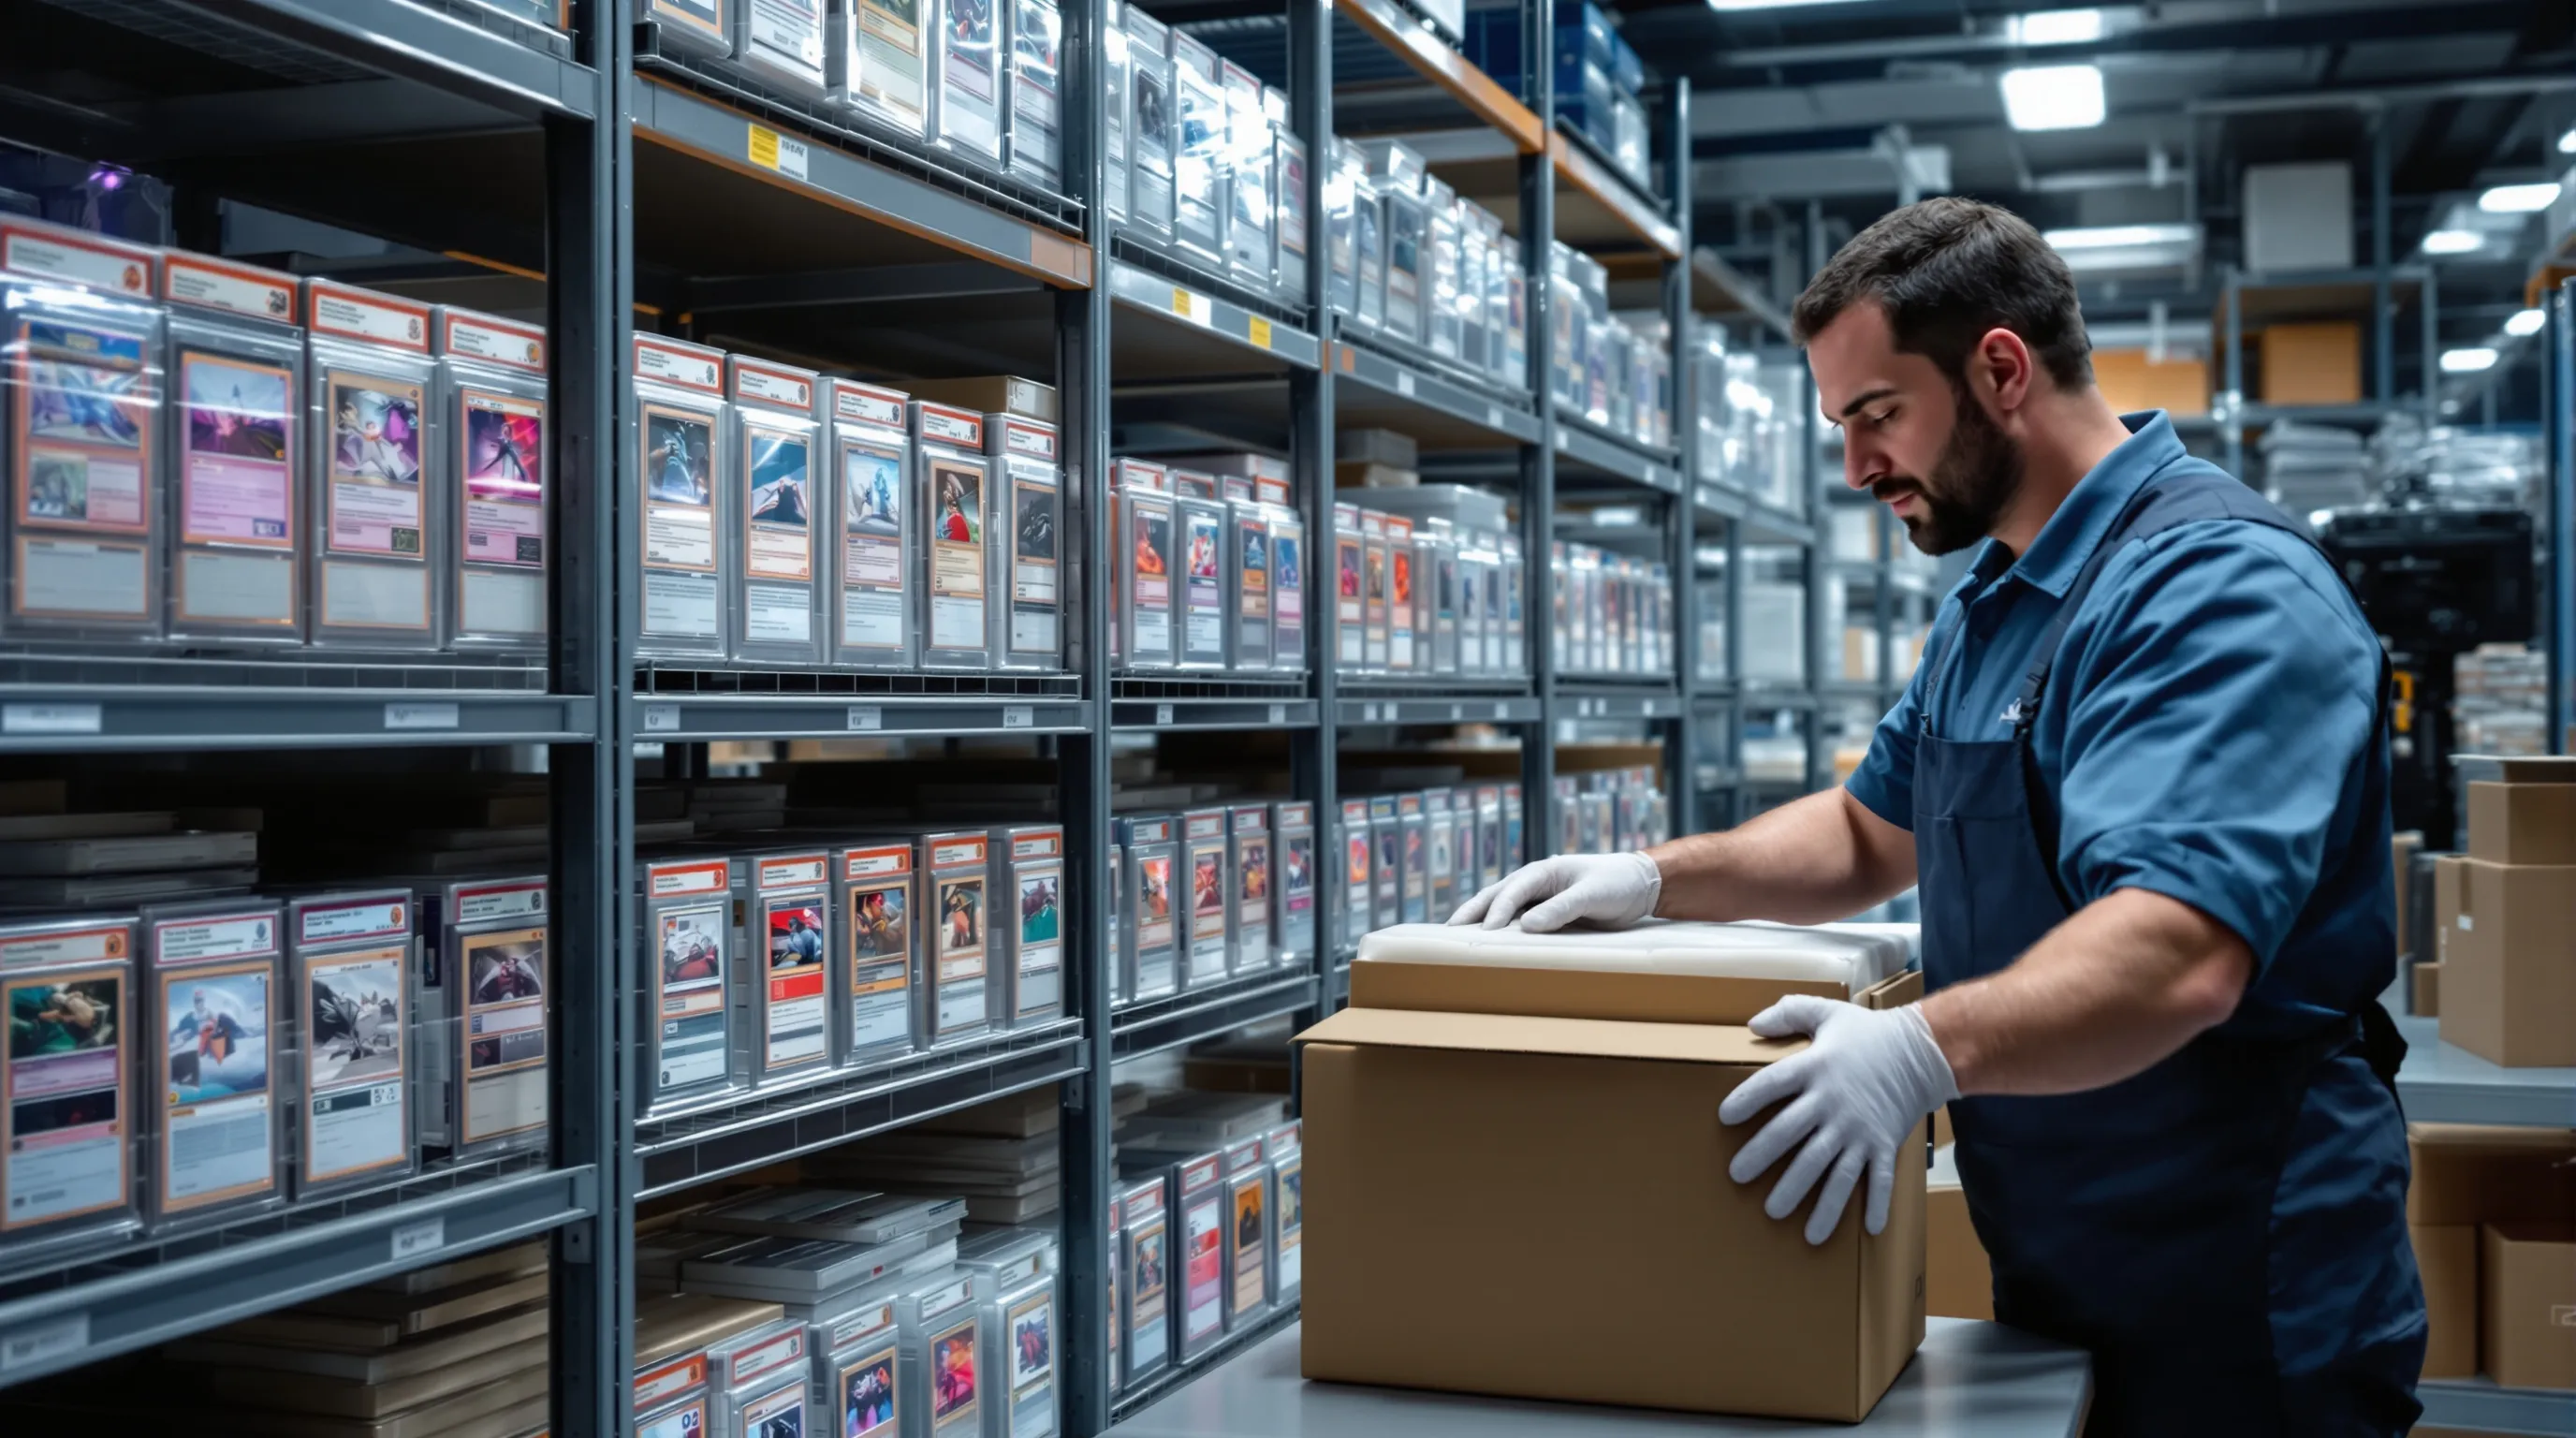
A vault window means the customer has paid while the cards are still on the shelf.
If you run a rip site or a live break and hold pulled cards for customers, this one's for you. I'll walk through what an underwriter reviews, how a 90-day vault compares to travel and pre-order accounts, and what to prepare before you apply. Then comes the part most merchants skip: keeping card tokens portable. A June 2026 r/PaymentProcessing thread spelled out the stakes. Merchants who switch processors without planning the token migration can end up "stuck in limbo for months."
A 90-day vault feels like a perk for collectors. An acquirer reads the same feature as one line in a risk file, right next to your stored balances and your buyback policy. In September 2026, a SeamlessChex underwriting team member summed it up: the processor "isn't really pricing 'trading cards'" but prepaid credit, a randomized outcome, and delayed physical fulfillment. The vault is where that delay shows. With acquirers now scoring risk transaction by transaction, it can't be hidden behind a collectibles label.
What does an underwriter actually see when you vault pulled cards?
Our underwriting team prices five things, not trading cards: prepaid credit, a randomized outcome, delayed physical fulfillment, stored balances, and buybacks of pulled cards.
Read your own model the way an underwriter would. Three questions come first:
- How long does a customer wait between paying and holding the card?
- How much customer money sits on your platform at any moment?
- Can a customer turn a pull back into cash through a buyback?
Ask yourself which of those three answers you could document today with records rather than estimates. On mainstream card platforms, settlement usually lands one to two days after the charge, and a processor's risk settings can shift that timing. The money lands in days. The card may not leave the vault for 90.
Vaulting is genuinely good for collectors. It saves shipping on cards they may sell back anyway. But every week a card stays unshipped is another week a non-receipt dispute stays possible, and that trade-off belongs to the merchant, not the customer.
We work with established businesses processing at least $25,000 per month, so the review starts from your real volume and history. That gap between settlement and delivery is exactly what high-risk credit card processing underwriters measure first, and it is why the closest benchmarks sit outside collectibles entirely.
How far ahead of the cards does your customer's money arrive?
A card payment feels finished the moment it is approved. On a platform that vaults pulled cards, the money and the merchandise run on two very different clocks.
Navdeep Yadav, who writes fintech explainers for people building payment products, starts with the approval itself. At authorization, he writes, "no money has actually moved yet." He calls it "a handshake, not the delivery." Clearing follows in a batch later that day. Settlement, when the funds actually move, usually comes one to two days after that.
On a vault platform, settlement is where the clocks split. The money reaches the merchant within a couple of days. The card the customer pulled can stay in storage until the vault window closes, which can mean weeks or months later.
| Stage of one order | When it happens | What moves |
|---|---|---|
| Charge approved | Real time | No money moves yet |
| Clearing | In a batch later that day | Transaction details pass between banks and networks |
| Settlement | Usually 1 to 2 days later | Funds reach the merchant |
| Vault window closes | Whenever your vault policy allows; our sources measured no typical length | The card ships or is bought back |
Settlement timing can also move. Yadav notes that one large payment provider settles merchant funds in bulk, "often next business day, depending on geography, currency, and risk settings." So even the short clock depends partly on how a processor reads your risk.
Our underwriting team's view of rip and mystery-pack platforms shows why the long clock matters more than what is inside the pack. Of the five things the team says a processor prices, three describe customer money on the platform before anything physical moves. With prepaid credit, the customer funds a balance before buying. Stored balances keep that money on the platform. Delayed fulfillment means the card ships later or stays vaulted. Our team places stored balances and buybacks "with stored balances and buybacks in the middle" of the shape. The vault window decides how long the delivery side of that gap stays open.
Five priced elements, two kinds of question
Set by the clock (money held ahead of the goods):
- Prepaid credit: the customer funds a balance before buying
- Stored balances: customer money held on the platform
- Delayed fulfillment: the card ships later or stays vaulted
Outside the clock:
- Randomized outcome: the pack or break spot delivers an unknown card
- Buybacks: the platform repurchases pulled cards, which gives customers a way to cash out
Grouping based on our underwriting team's description of how processors price rip, mystery-pack and break platforms, September 2026.
Two of the elements do not fit the clock at all, and a shorter vault would not answer them. The randomized outcome is about what arrives, not when it arrives. Buybacks run the other way, sending money from the platform back to the customer, and our team treats them as a cash-out path. A merchant could ship every card the next morning and still need to explain both. Whether a processor treats a randomized pull as a classification question is something to ask directly, before you apply.
Yadav's advice to product teams helps with the clock side. He says anyone building wallets or merchant dashboards must show "settled balance vs. authorized transactions," and that teams handling refunds or disputes need to know where each transaction sits in its lifecycle. He was writing for fintech builders, not underwriters. Still, on a vault platform the lifecycle keeps going after settlement: a settled order can still be vaulted, shipped or bought back. A merchant who can show where each order stands is in a position to describe how each element is controlled. That description is what our team says the application should contain, rather than presenting the business as a card shop.
Most of the risk profile, then, is a stretch of time: it starts when settlement lands and ends when the card leaves the vault. The vault window decides how long that stretch runs. Randomness and buybacks fall outside it and need their own answers.
- Write down your own timeline for a typical order: when the charge is approved, when funds settle, and when the card ships or is bought back. Put the longest case, the full vault window, in your application.
- Ask any processor, us included, whether your vault window will affect your settlement timing.
- Report balances by state: authorized, settled, vaulted, shipped, bought back. When a dispute arrives, you can show where that order sits.
- Describe buybacks as a separate flow of money in your application, and explain how you control it, instead of folding it into fulfillment.
- Ask each processor how it views a randomized pull, and whether it has already boarded platforms that combine stored balances, vaulting and buybacks.
How we checked this
We used a fintech explainer on how card payments move through authorization, clearing and settlement, and our own underwriting team's notes on rip, mystery-pack and break platforms. The five-part risk profile comes from our team. None of our sources measured how long platforms actually hold cards, so the vault window in this section describes the scenario the article examines. Yadav describes typical card flows, so the settlement timing will differ by provider and setup. We board merchants in this segment, so we have a stake in how this question is answered. Still unknown: how long customers actually leave cards in vaults, and whether dispute rates rise as the window gets longer. None of our sources measured either one.
- Navdeep Yadav, fintech concepts explainer on Medium, August 2025.
- SeamlessChex underwriting team, internal notes on how processors price card rip, mystery-pack and break merchants, September 2026.
How does a 90-day vault compare to travel and pre-order accounts?
A long vault sits much closer to travel and pre-order than to retail: the customer pays today, and delivery happens weeks later.
Travel and pre-order are the deferred-delivery accounts underwriters already know well. Money comes in now, and the trip or product shows up later. A dispute can arrive long after the funds have settled. When our underwriting team looks at a vaulted rip or break platform, the vault is the delayed physical fulfillment piece of that same shape, written out on a calendar.
| Merchant model | Customer pays | Customer receives | Underwriting exposure |
|---|---|---|---|
| Card-present retail | At the counter | At the counter | Little delivery exposure |
| Ship-now e-commerce | At checkout | Within days | Short non-receipt window |
| Pre-order | At checkout | On a future release date | Paid before goods ship |
| Travel | At booking | On the travel date | Long gap between payment and delivery |
| Vaulted pulls (up to 90 days) | At purchase | When the customer asks to ship | Deferred delivery plus stored goods |
Card networks treat authorization as a handshake, not the delivery. Put plainly, when a payment is approved, no money has moved and no goods have changed hands. So ask any processor you speak with whether it already boards travel or pre-order merchants, and how it set their payout and reserve terms.
The tooling is changing too. Acquirers are increasingly moving to real-time adaptive risk scoring, driven by AI-enabled fraud and stricter scheme controls such as Visa's VAMP thresholds. Fixed vertical labels matter less. How your transactions actually behave matters more.
Here's the honest gap. No published dataset we've seen compares chargeback rates on ship-later and ship-now orders. Until one exists, your own dispute history by fulfillment timing is the best evidence you can bring to a merchant payment processing review, and it shapes the reserve conversation that follows.
What should you prepare before applying with a vault window?
Come in as an established, operating business with steady card volume, then show the underwriter exactly how your vault works and how each risk is controlled.
Before you apply, I'd gather five things:
- Written vault terms. How long a card can sit, how a customer requests shipping, and what happens when the window closes.
- An honest business description. Name all five parts of the shape (prepaid credit, randomized outcome, delayed fulfillment, stored balances, buybacks) and the control behind each one.
- Dispute history split by fulfillment. Separate vaulted orders from ship-now orders so the reviewer can see the difference for themselves.
- Complete transaction data. Send IP address, device ID, billing address, and customer email on every authorization.
- Tokens you control. Store cards in a gateway that is not tied to a single processor.
Step two matters most. Then show the control behind each part, for example who approves a buyback request before money leaves the platform. The better question to ask any processor is whether it already boards platforms shaped like Courtyard or Rips by Triumph. If it does, it has priced this risk before.
Step four is about more than fraud. Missing authorization fields lower issuer confidence and raise false declines. Clean data reads as a well-run account. That counts for a lot when the review is already weighing delayed delivery.
Step five buys you leverage. A 2024 r/PaymentProcessing thread called moving stored cards "a token migration. Very common," and one commenter advised, "Keep the gateway the same and change processors." Most merchants never plan for leaving. A vault merchant should, the same way an online travel agency payment processing setup is built around money collected long before the trip.
Which credit card processing solutions work best for high-risk merchants with a vault?
The best fit is a processor that already underwrites deferred delivery and has boarded platforms shaped like yours, so your vault is priced as a known risk, not a surprise.
Settlement keeps getting faster, and real-time rails are pushing it toward seconds. Delivery from a vault doesn't speed up. I expect that widening gap to shape more reserve and payout decisions, not fewer. Merchants who write down their vault terms, track disputes by fulfillment timing, and keep their tokens portable will negotiate from a stronger position. Plan any token migration alongside the processor move itself. Leave it for later and you can lose months to a stalled cutover.
Frequently Asked Questions
What else do merchants ask about vault windows and underwriting?
How do processors handle delayed shipping on mystery packs?
They treat it as deferred delivery, meaning the customer pays now and receives the goods later. Underwriters look at how long cards sit before shipping, how much customer money is held, and how disputes behave over that window. A clear, written vault policy makes that review much easier.
Does a 90-day vault automatically mean a bigger reserve?
Not automatically. No published data ties reserve size to vault length. Terms are set account by account, and your own dispute history on vaulted orders carries real weight.
What is a token migration?
A token migration moves your customers' stored card tokens from one processor or gateway to another, so they don't have to re-enter their cards. Plan it together with any processor switch. Treat it as an afterthought and it can stall for months.
How quickly can a vaulted platform get set up?
SeamlessChex offers same-day onboarding once underwriting has reviewed your business. Start at seamlesschex.com/contact.
Can I accept ACH alongside cards?
Yes. Credit card processing comes first, and ACH is available as a second rail, online or in person.
Written by
Lily Flanigan
Operations Manager, SeamlessChex
Lily Flanigan is Operations Manager at SeamlessChex, a credit card processing and fintech payments platform recognized on the Inc. 5000, where she focuses on operations and process optimization.
Connect on LinkedInSeamlessChex works with established businesses processing a minimum of $25,000 per month.