


Quick Answer
Underwriters price a card break business as prepaid credit, a randomized outcome and delayed physical fulfillment. Approval turns on three signals: fulfillment reliability, chargeback control and volume predictability.
Stored balances and buybacks sit in the middle of that profile. Document all three signals before you apply. A file that shows sealed product opened as sold, disputes answered with records and steady monthly card volume is hard to decline. Leave any of the three out, and the reviewer fills the gap with caution.
Key Points
- The SeamlessChex underwriting team prices break and rip platforms as five elements: prepaid credit, a randomized outcome, delayed physical fulfillment, stored balances and buybacks.
- In July 2024, Maryland passed the Gift Card Scams Prevention Act of 2024, which mandates secure packaging, state registration for gift card sellers and employee training.
- A 2000 Entrepreneur article reported that card issuers could bar online merchants with chargeback rates above 1 percent, so ask any processor for its current limit.
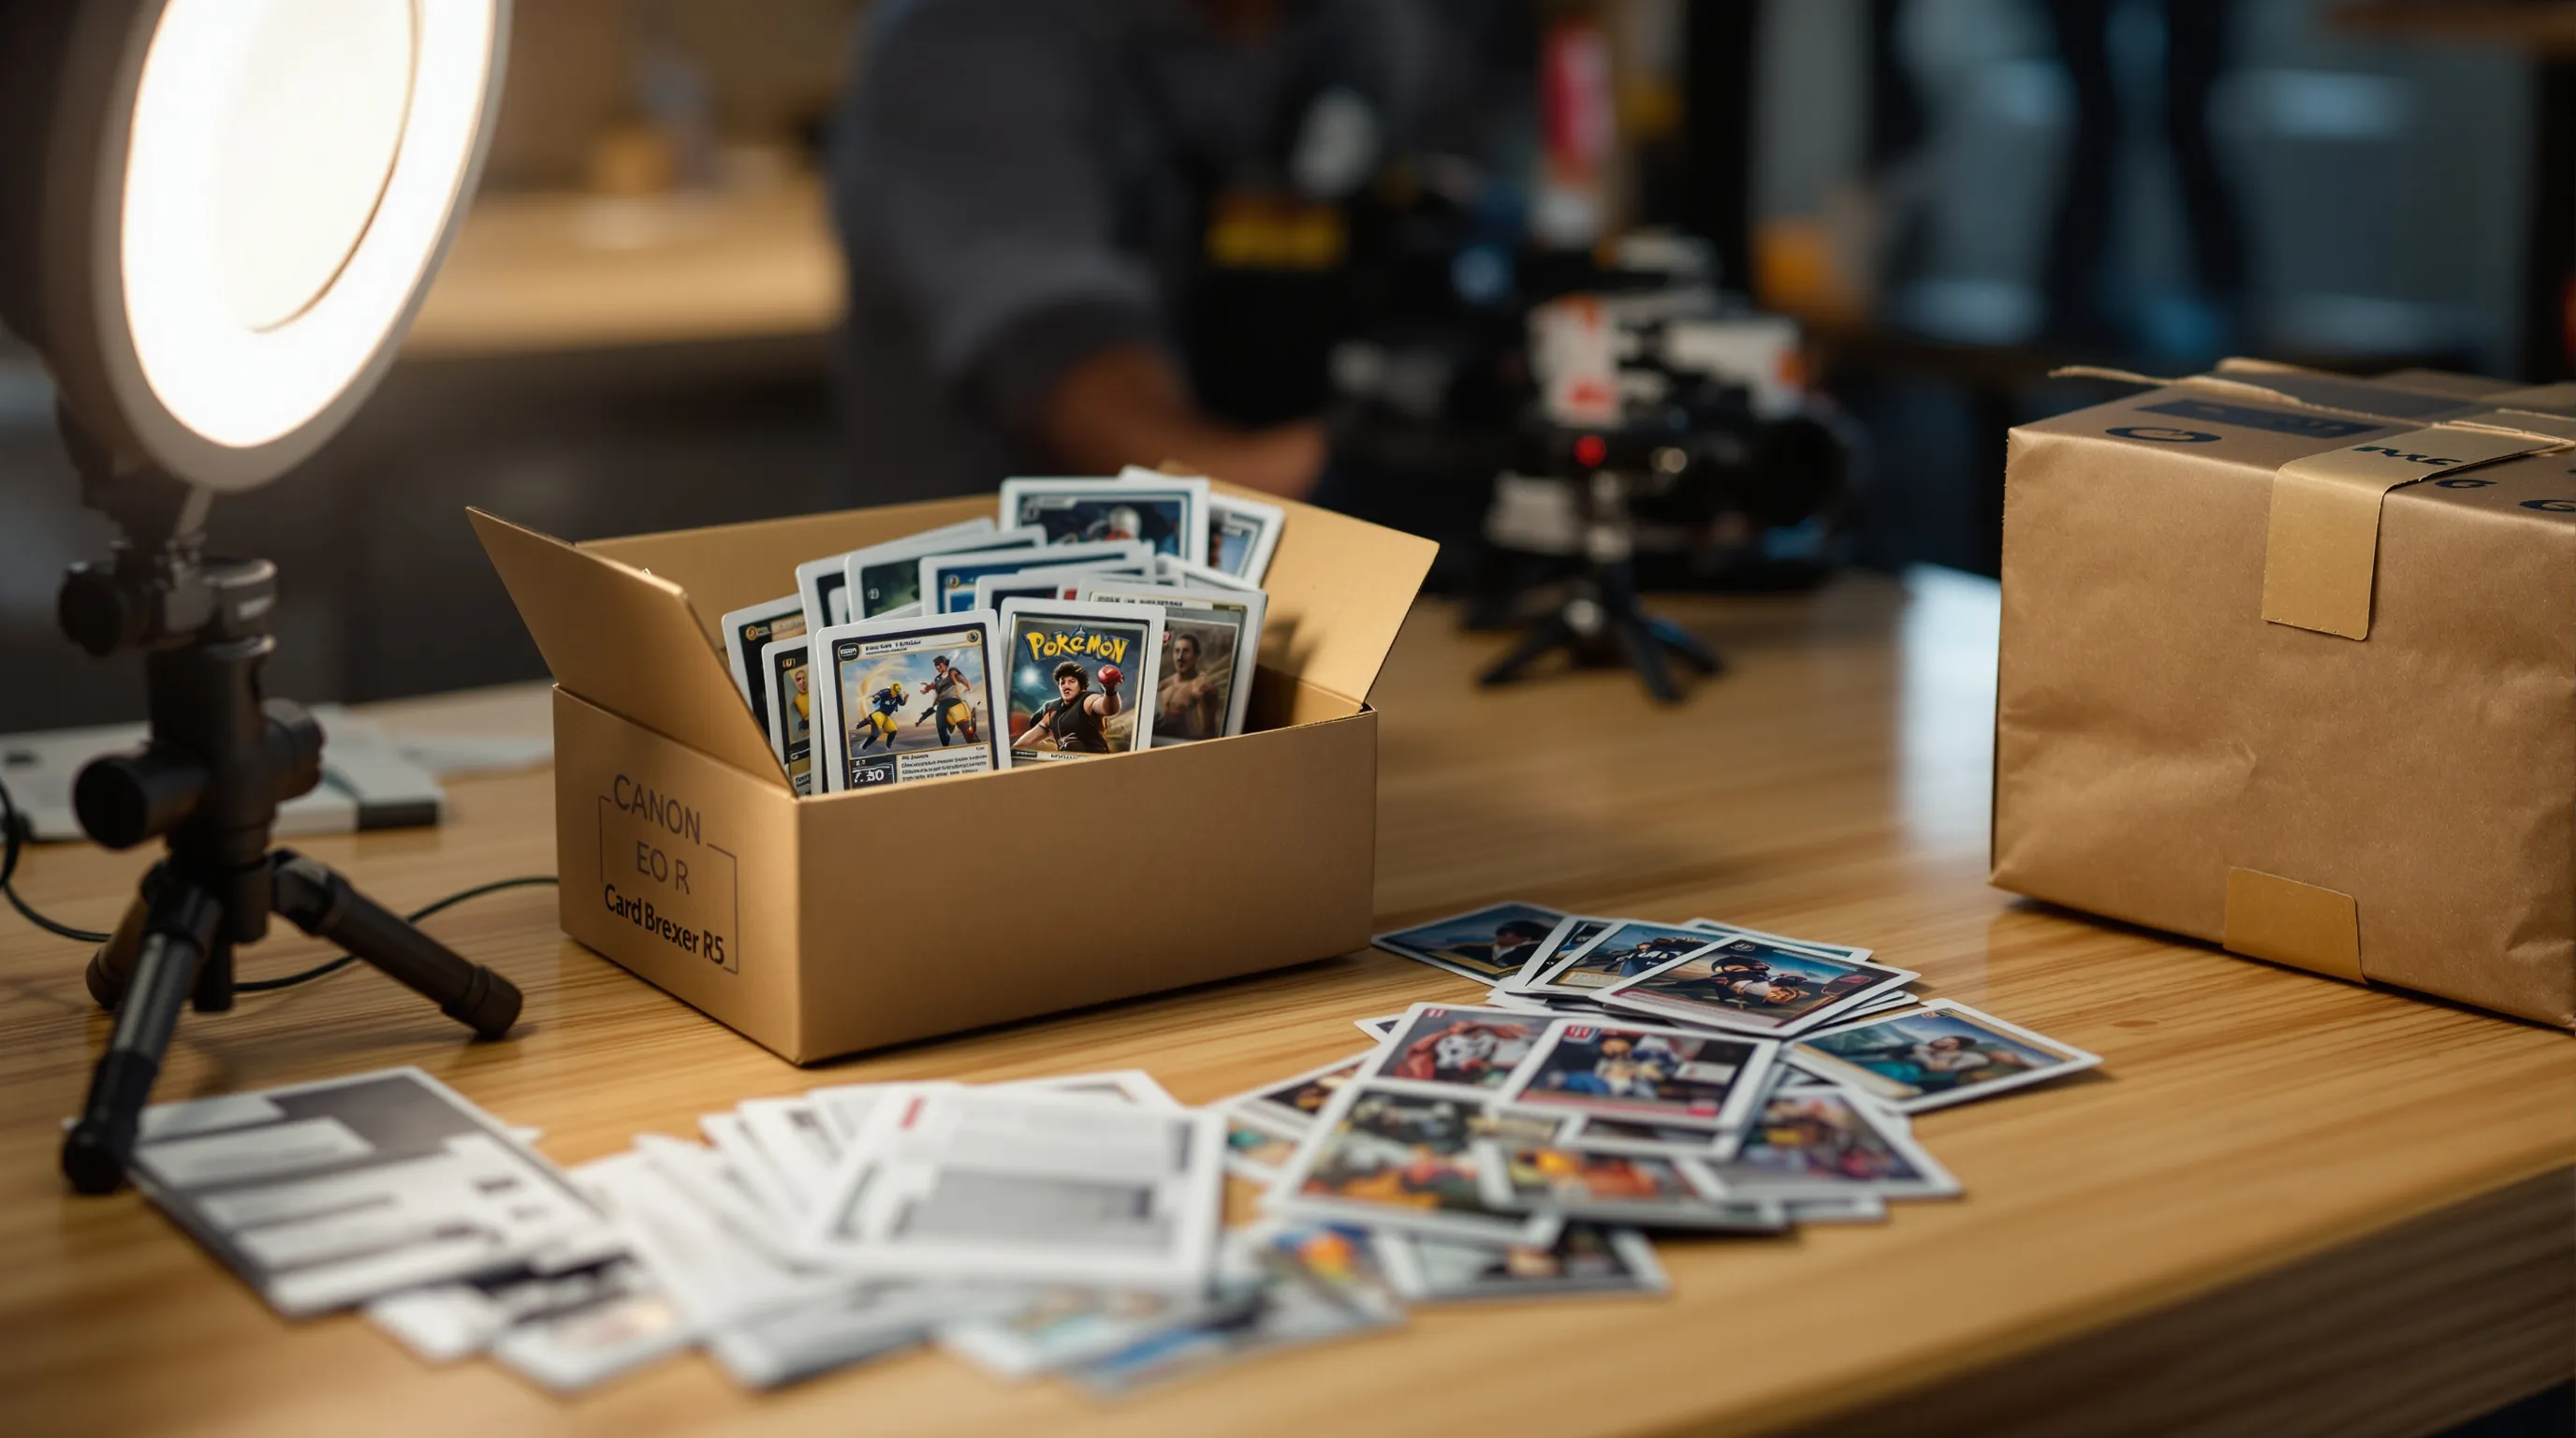
Sealed product, a recorded break and a shipment ready to go: the records an underwriter wants to see.
For a card break platform, the best fit is a processor that already underwrites prepaid credit, randomized outcomes and delayed physical fulfillment, the shape behind Courtyard and Rips by Triumph.
For a breaker, "secure" has two meanings. One is the transaction. The other is the account itself: whether it stays open after a heavy week of breaks, a run of late shipments or a buyer who disputes a pull they did not like.
The second meaning is where break platforms get hurt. A high-risk merchant account is a credit card merchant account underwritten for a business model that standard processors decline or later close, and for breakers the underwriting is the real product. Our underwriting team reads a rip or break platform as five priced elements: prepaid credit, a randomized outcome, delayed physical fulfillment, stored balances and buybacks. A processor that has never boarded that combination tends to treat it as an odd retail account.
The comparables are public. Courtyard sells digital packs of vaulted, graded physical cards. Rips by Triumph sells mystery packs paid by Visa, Mastercard, Apple Pay, PayPal or Venmo, according to its public app-store and review listings in August 2026. The model itself runs on mainstream card rails.
I find the five elements far easier to prepare for once they are grouped into three signals an underwriter can actually test: fulfillment reliability, chargeback control and volume predictability. This guide is written for established breakers and rip platforms with real processing history, not sellers still planning a first stream. It starts where the underwriter starts, with what is being priced.
Most card breakers who get declined never learn what the underwriter was actually looking at. The application describes a card shop. The underwriter sees a different business entirely.
Our underwriting team at SeamlessChex frames it this way: a rip or break platform is priced as prepaid credit, a randomized outcome and delayed physical fulfillment, with stored balances and buybacks running through the middle. Each of those five elements raises its own question. Can you deliver exactly what was sold? Can you defend a disputed pull? Can anyone predict how money enters, sits on and leaves your platform?
Those questions reduce to three signals: fulfillment reliability, chargeback control and volume predictability. My position is simple. So the useful question before applying is which of the three your current records already prove, and which one they leave blank. The research section below walks through what each signal needs on paper.
None of this requires you to change how you run breaks. It requires you to make the business legible. Below, I walk through what the underwriter prices, why generalist processors so often balk, and exactly what to assemble before you apply for a high-risk credit card merchant account.
Questions this article answers
Questions this guide answers
- What do underwriters look for in a card break business?
- Why do Stripe and PayPal shut down card break sellers?
- What should I document before applying for a high-risk merchant account for my breaks?
Start with the first one. Everything after it depends on how an underwriter reads your business.
What does an underwriter actually price in a card break business?
An underwriter prices prepaid credit, a randomized outcome and delayed physical fulfillment, with stored balances and buybacks sitting in the middle. Trading cards are only the inventory.
Before you describe your business on an application, map it against the five elements our underwriting team at SeamlessChex prices on every rip, mystery-pack and break file:
- Prepaid credit: the customer funds a balance before buying anything.
- Randomized outcome: the pack or break spot delivers a card nobody can name in advance.
- Delayed physical fulfillment: the card ships later or stays vaulted.
- Stored balances: customer money is held on the platform.
- Buybacks: the platform repurchases pulled cards, which creates a cash-out path.
The way our team puts it, the processor "isn't really pricing 'trading cards'" at all. Instead, "it's pricing prepaid credit, a randomized outcome, and delayed physical fulfillment, with stored balances and buybacks in the middle." That gap explains why a breaker who applies as a card shop so often gets a confused follow-up or a flat decline. The application describes one business. The underwriter is evaluating another.
The common assumption is that a break platform is simply a collectibles retailer with an entertaining sales channel. In our review, that framing misdescribes the business, and a misdescribed business is hard to approve with confidence.
Insurance underwriting offers a useful contrast. UK study material for the Chartered Insurance Institute's IF3 unit notes that, under the Equality Act 2010, insurers may impose specific underwriting terms only when they are based on "information that is relevant to the assessment of the risk." Card acceptance is a different discipline, but the principle travels well. A decision follows the risk information in front of the reviewer. If your file talks about rookie cards and hobby passion, you have handed over the wrong information.
Stored balances deserve particular attention. In a 2024 Javelin Strategy & Research report covered by PaymentsJournal, Director of Prepaid Jordan Hirschfield compared deposited customer funds to a toll tag and said "to them, that money is a liability, just like a gift card." He was describing stored-value accounts in a different industry, yet the mechanics of customer money held ahead of delivery look much the same on a break platform.
Who buys matters too. A 2022 Brand Minds article put the number of baseball card collectors at over 4 million in 1993 and only around 900,000 by the time it was written, so many break platforms lean on a smaller pool of heavier buyers, and a few disputed breaks from those buyers can move a reviewer's numbers quickly. The five elements collapse into three signals you can document:
- Fulfillment reliability covers delayed fulfillment and the randomized outcome. Can you prove what was opened and that it reached the buyer?
- Chargeback control covers the randomized outcome and prepaid credit. Can you win a dispute from a buyer unhappy with their pull?
- Volume predictability covers stored balances and buybacks. Can a reviewer forecast how money enters, sits and leaves your platform?
In practice, the file decides the conversation. A clear map shortens it. When you later compare merchant payment processing solutions, the first question worth asking any provider is whether it already boards businesses built on this shape, because a provider that has never priced prepaid credit and delayed fulfillment will read your application through a retail lens.
Which leaves the question most breakers arrive with: why do the mainstream processors keep saying no?
What does a breaker's paper trail need to prove to an underwriter?
Ask a breaker what running a break involves and you get a list of chores. Read that same list the way an underwriter does, and every chore becomes evidence.
In June 2021, a programmer who ran card breaks shared a free tool he had built on r/sportscards. He built it after learning "there's a lot of steps involved (procuring wax, listing, finding buyers, breaking, sorting, shipping, etc.)" The app handled break-by-team assignments, randomized slots and YouTube integration. One reply asked how he took payments. The commenter had been trying to open a store, and payment providers had told him "they won't accept me" because he had no documentation to sell licensed NFL, NBA and Pokémon products.
A single commenter proves no pattern. Still, his reply points to a gate in front of any review of disputes or volume: proof of where the product comes from and of your right to sell it. The other lesson is in the poster's list of chores.
Our underwriting team describes a break platform as five priced elements, as the previous section sets out. Put those elements beside the breaker's chores and each one has a step where it leaves a record. Each record then speaks to one of three signals: fulfillment reliability, chargeback control or volume predictability.
| Priced element | What the underwriter is weighing | Signal | Record that answers it |
|---|---|---|---|
| Before any of the five: product sourcing | Whether you can legally sell the licensed product | Gate | Purchase invoices and licensing or distribution documents for your sealed wax |
| Prepaid credit | Money collected before any card ships | Fulfillment reliability | Slot sales list tied to a specific break |
| Randomized outcome | Disputes over what a buyer received | Chargeback control | Written randomization method and the recorded break |
| Delayed fulfillment | Non-receipt claims | Fulfillment reliability | Sorting log and tracking for each team or slot |
| Stored balances | Refund exposure | Volume predictability | Balance ledger and refund policy |
| Buybacks | Money flowing back out | Volume predictability | Buyback ledger showing what was repurchased, from whom, and how it was paid |
Stored balances and buybacks need the most care. In 2024, Jordan Hirschfield, director of prepaid at Javelin Strategy & Research, described the accounting behind customer deposits in mobile sports betting, a very different prepaid market from card breaks.
"to them, that money is a liability, just like a gift card."
Jordan Hirschfield, Director of Prepaid, Javelin Strategy & Research, 2024
The mechanics carry over even though the businesses differ. When a customer funds a balance, the platform owes either cards or money back. A buyback opens a second route for money to leave. Underwriters want refunds and money movement spelled out for exactly these reasons.
Federal prepaid rules are a separate question. Regulation E's definitions at 12 CFR 1005.2 count a prepaid account as a type of consumer account. One part of the definition covers accounts "marketed or labeled as "prepaid"" that are "redeemable upon presentation at multiple, unaffiliated merchants." A balance spendable on only one break platform does not plainly match that wording. The definition continues past that clause, and we offer no legal opinion here. Ask your counsel.
Disputes are where the records pay for themselves. A 2000 Entrepreneur explainer for online merchants set out the mechanics. When a cardholder disputes a charge, the merchant has to prove the sale. If it cannot, "the bank awards a charge-back, crediting the consumer's account and debiting the merchant's account." The same article said issuers may bar merchants with "charge-back rates of more than 1 percent." None of our sources gives a current threshold, so read that figure as background. When the outcome is random, the merchant has to show two things: the draw was fair, and the cards went out. The randomized slots and recorded stream in that 2021 tool are early versions of that proof.
Volume is the most direct signal, and for us it starts with one number. We require at least $25,000 in monthly processing, and we board established businesses rather than pre-launch startups.
Line the evidence up and the breaker's chore list and the underwriter's checklist turn out to be the same document, written in two vocabularies. Each step of a break either produces proof or leaves a gap. One requirement sits outside the three signals, though: sourcing paperwork. For one commenter in 2021, lacking it ended the conversation.
- Put proof of where your sealed product comes from, and your right to sell the licensed brands in it, at the front of the file.
- Keep one record per break: the slot sales list, how slots or teams were randomized, the recorded stream, and the shipment tracking for every buyer's cards.
- Describe stored balances and buybacks as money you owe customers, write down how refunds and cash-outs work, and ask your counsel whether federal prepaid account rules reach your balances.
- Ask any processor, us included, what chargeback rate it treats as the limit for your business today, since the 1 percent figure people repeat comes from 2000.
- Compare your monthly card volume to the processor's minimum before you apply. Ours is $25,000, for established businesses only.
How we checked this
Our sources were a 2021 Reddit thread written by a working breaker, a 2024 trade article on a Javelin prepaid report, a 2000 small-business article on chargebacks, the federal Regulation E definitions, and our own underwriting material. The five priced elements (September 2026) and the $25,000 minimum (July 2026) are ours. The table mapping each element to a signal is our own reading. The Reddit thread includes one commenter's rejection, which is an anecdote, and the praise in that thread comes from the poster's own customers. Hirschfield was describing a different industry. The chargeback article is from 2000. We read only part of the Regulation E text, and nothing here is legal advice. We board break and rip merchants, so we have a commercial stake in this topic. Still unknown: today's chargeback limits for this segment, how often sourcing documents cause declines, and whether prepaid account rules apply to break balances.
- r/sportscards, breaker's thread on a card break web app, June 3, 2021.
- PaymentsJournal, article on Javelin's 2024 prepaid regulatory outlook, November 15, 2024.
- Entrepreneur, article on online credit card fraud and charge-backs, May 1, 2000.
- eCFR, 12 CFR 1005.2 Regulation E definitions, retrieved November 7, 2026.
- Seamless Chex underwriting team on break and rip merchants, relayed by Chris Daniels, September 4, 2026, and merchant qualification minimum from Evan Albert, July 2026.
Why do mainstream processors like Stripe and PayPal decline or shut down card break businesses?
Generalist processors are generally set up for standard retail. A break platform combines prepaid credit, a randomized outcome and delayed fulfillment, which is a shape many of them are not built to price.
The friction usually shows up in three places before anyone talks about rates:
- Sourcing documentation. Providers ask for proof that you can sell licensed product, and many breakers have never assembled it.
- Prepaid exposure. Customer balances held before delivery resemble products that regulators are actively tightening.
- Dispute exposure. A randomized pull followed by a delayed shipment gives an unhappy buyer two separate reasons to dispute.
The first point is visible in hobby forums. Sellers there describe being turned away by payment providers because they lacked documentation to sell licensed NFL, NBA and Pokémon products. Nothing in that decline was about fraud. The application simply could not show where the inventory came from.
The prepaid point is not theoretical either. In July 2024, Maryland passed the Gift Card Scams Prevention Act of 2024, which mandates secure packaging, requires merchants selling gift cards to register with the state and adds mandatory employee training. Federal attention followed a similar line: the U.S. Department of Homeland Security launched Operation Red Hook with local law enforcement to identify gift card draining criminals. None of this targets breakers directly. It still shapes how a risk team reads a customer balance that sits on your platform for weeks.
Dispute risk has worried banks for a long time. Back in 2000, Entrepreneur reported that some banks would "flat-out refuse to work with Internet companies because of the risk of charge-backs." Online card acceptance has matured enormously since then, yet the instinct survives in any review of a card-not-present seller whose product is a live, unrepeatable event.
Put those three pressures together and the pattern behind abrupt closures becomes easier to see. Fast self-serve onboarding is not the same as underwriting. An account opened without a real review of your business shape can be reviewed later, at the worst possible moment, and closed. If a closure has already left your business on a terminated merchant file, our guide to TMF/MATCH list merchant account approval explains how established merchants rebuild card acceptance.
The fix is not to hide the shape. Our view at SeamlessChex is that the real qualification question for a prospective processor is whether it already boards platforms like yours, because any processor already comfortable with Courtyard or Triumph has underwritten this shape before. A processor that knows the shape asks better questions. It also stops treating every break as an anomaly.
Contrary to what many breakers expect, a decline from a generalist is rarely a verdict on the business itself. More often it reflects a file that never explained prepaid credit, delayed fulfillment and dispute handling in terms an underwriter can approve, which turns the practical question toward what, exactly, belongs in that file.
What should a card breaker document before applying for a high-risk merchant account?
Document how money moves, how every break is recorded and delivered, and how disputes get answered. Then organize that proof under fulfillment reliability, chargeback control and volume predictability.
I would assemble these items before speaking to any processor:
- A funds flow map. Show how prepaid credit, stored balances and buybacks are held, reconciled and paid out.
- Sourcing records. Keep invoices or distributor records for sealed product, including documentation for licensed lines.
- Outcome disclosure. Save the exact wording buyers see before purchase, including how spots are assigned, by team or at random.
- Break records. Tie each recording and slot log to a specific order number.
- Delivery and vault records. Keep tracking for shipped cards and statements for vaulted ones.
- A dispute playbook. Write down your refund policy, your billing descriptor and the evidence you send for each dispute reason.
- Processing history. Pull statements that show steady monthly volume over time.
Items two, four and five prove fulfillment reliability. Items three and six prove chargeback control. Items one and seven prove volume predictability. The research section above walks through how an underwriter reads these records.
Why so much paper? Back in 2000, Entrepreneur explained the mechanics plainly: when a cardholder disputed a transaction, the bank required the merchant to show proof of purchase, and a merchant who could not produce it lost the chargeback, with the consumer's account credited and the merchant's debited. The same 2000 article reported that, at the time, card issuers could bar online merchants whose chargeback rates ran above 1 percent. Before you apply, ask each processor which records it accepts as proof of delivery for a vaulted card compared with a shipped one. The burden of proof has not moved.
For a breaker, that burden is unusually heavy. Your buyer may have watched the break live, cheered the pull and still claimed the package never arrived. Without a recording tied to the order and tracking tied to the recording, you are arguing from memory.
Insurance study material makes a related point. Chartered Insurance Institute flashcards on the underwriting process note that commercial underwriting is generally more complicated because "risks are less homogeneous." A break platform is about as non-homogeneous as retail risk gets. Your file's job is to make each piece look ordinary.
One threshold sits ahead of all of it. SeamlessChex works with established businesses processing at least $25,000 per month, and that applies across every vertical we board. If you are still pre-launch, treat this list as something to build toward over your first months of trading rather than something to submit next week.
A practical note on rails. Card acceptance carries the weight of a break business, and it should lead your application. Some platforms also add bank transfers as a secondary option for larger balance top-ups, and our page on how to accept ACH payments covers how that second rail fits beside a credit card merchant account. It supports the card program. It does not replace it.
Once the documents exist, the harder question is which of them an underwriter will lean on first, and how much weight each one actually carries.
Where is card break underwriting headed next?
Expect underwriters to treat break platforms more like holders of prepaid value with delayed delivery. Files that already document fulfillment, disputes and money movement will stay ahead of that shift.
Our underwriting team already prices the shape as prepaid credit, a randomized outcome and delayed fulfillment. Over the next 12 to 24 months, I expect stored balances and buybacks to draw even closer review. Prepaid enforcement was already active in 2024. It is unlikely to soften.
I cannot give you a published approval rate for files that document all three signals. The evidence does not show one, and I will not invent it. What I can say is how persuasion works in any review. A career coach on the Get Hired in Medical Sales podcast tells candidates to bring specific, real examples an interviewer cannot argue with. Underwriting rewards the same discipline.
So build the file before you need it. A recording tied to an order. A balance ledger that reconciles. A dispute answered with proof rather than memory.
Frequently Asked Questions
What else do card breakers ask about merchant account underwriting?
These answers cover the follow-up questions breakers tend to raise once the main file is built: classification, buybacks, sealed product, how to describe the business and how quickly processing can start.
Do underwriters treat a card break as gambling?
Underwriters ask because a break sells a randomized outcome: a known price for an unknown card. Our underwriting team prices that as one element of the business, next to prepaid credit and delayed physical fulfillment. It is not the whole profile. Answer the classification question in writing before anyone raises it.
Do buybacks change how my application is reviewed?
Yes. A buyback is the platform repurchasing a card a customer pulled, which opens a path for money to flow back out. Our review weighs it alongside stored balances, so describe who can sell back, when, and on which rail the payout moves.
Why would an underwriter care whether product was sealed?
Tampering is a known prepaid fraud pattern. A 2024 prepaid regulatory review described criminal networks swapping large quantities of gift cards for tampered versions so they could claim the funds consumers had loaded. A break platform faces the mirror question: was the box sealed when the stream started? Unedited break recordings answer it.
Can I apply as an ordinary card shop?
I would not. Our team's view is that a platform applying as a card shop misdescribes its business, because the processor is pricing prepaid credit, randomized outcomes, delayed fulfillment, stored balances and buybacks together. Commercial risks vary too much for a generic retail label to carry them, so describe that shape and how you control each piece.
How quickly can an established break platform start processing cards?
SeamlessChex offers same-day onboarding with no contracts, with credit card processing first and ACH as a secondary rail. Speed still depends on the file. Bring specific, real records a reviewer cannot argue with, then start the application through our contact page.
Written by
Jonathan Albert
Co-Founder, SeamlessChex
Jonathan Albert is Co-Founder of SeamlessChex, a credit card processing and fintech payments platform recognized on the Inc. 5000.
Connect on LinkedInSeamlessChex works with established businesses processing a minimum of $25,000 per month.