


Quick Answer
Underwriters board a rip site on proof it has run its money cleanly: customer balances honored, cards delivered, and buybacks paid. A few clean months on that record outweigh raw volume.
Acquirers price rip, mystery-pack and break platforms as prepaid credit, a randomized outcome, delayed physical fulfillment, stored balances and buybacks. No published benchmark fixes a minimum number of months for each element. So the platform's own records carry the file, and the next move is finding a processor that has boarded this shape before.
Key Points
- SeamlessChex's underwriting team describes rip, mystery-pack and break platforms as prepaid credit, a randomized outcome, delayed physical fulfillment, stored balances and buybacks.
- An April 2026 r/PaymentProcessing commenter said "3 months of clean data beats every other application asset," with chargebacks kept below about 1%.
- A February 2026 r/smallbusiness post showed a newly approved high-risk merchant held to a 10% rolling reserve for six months, despite good credit and no chargebacks.
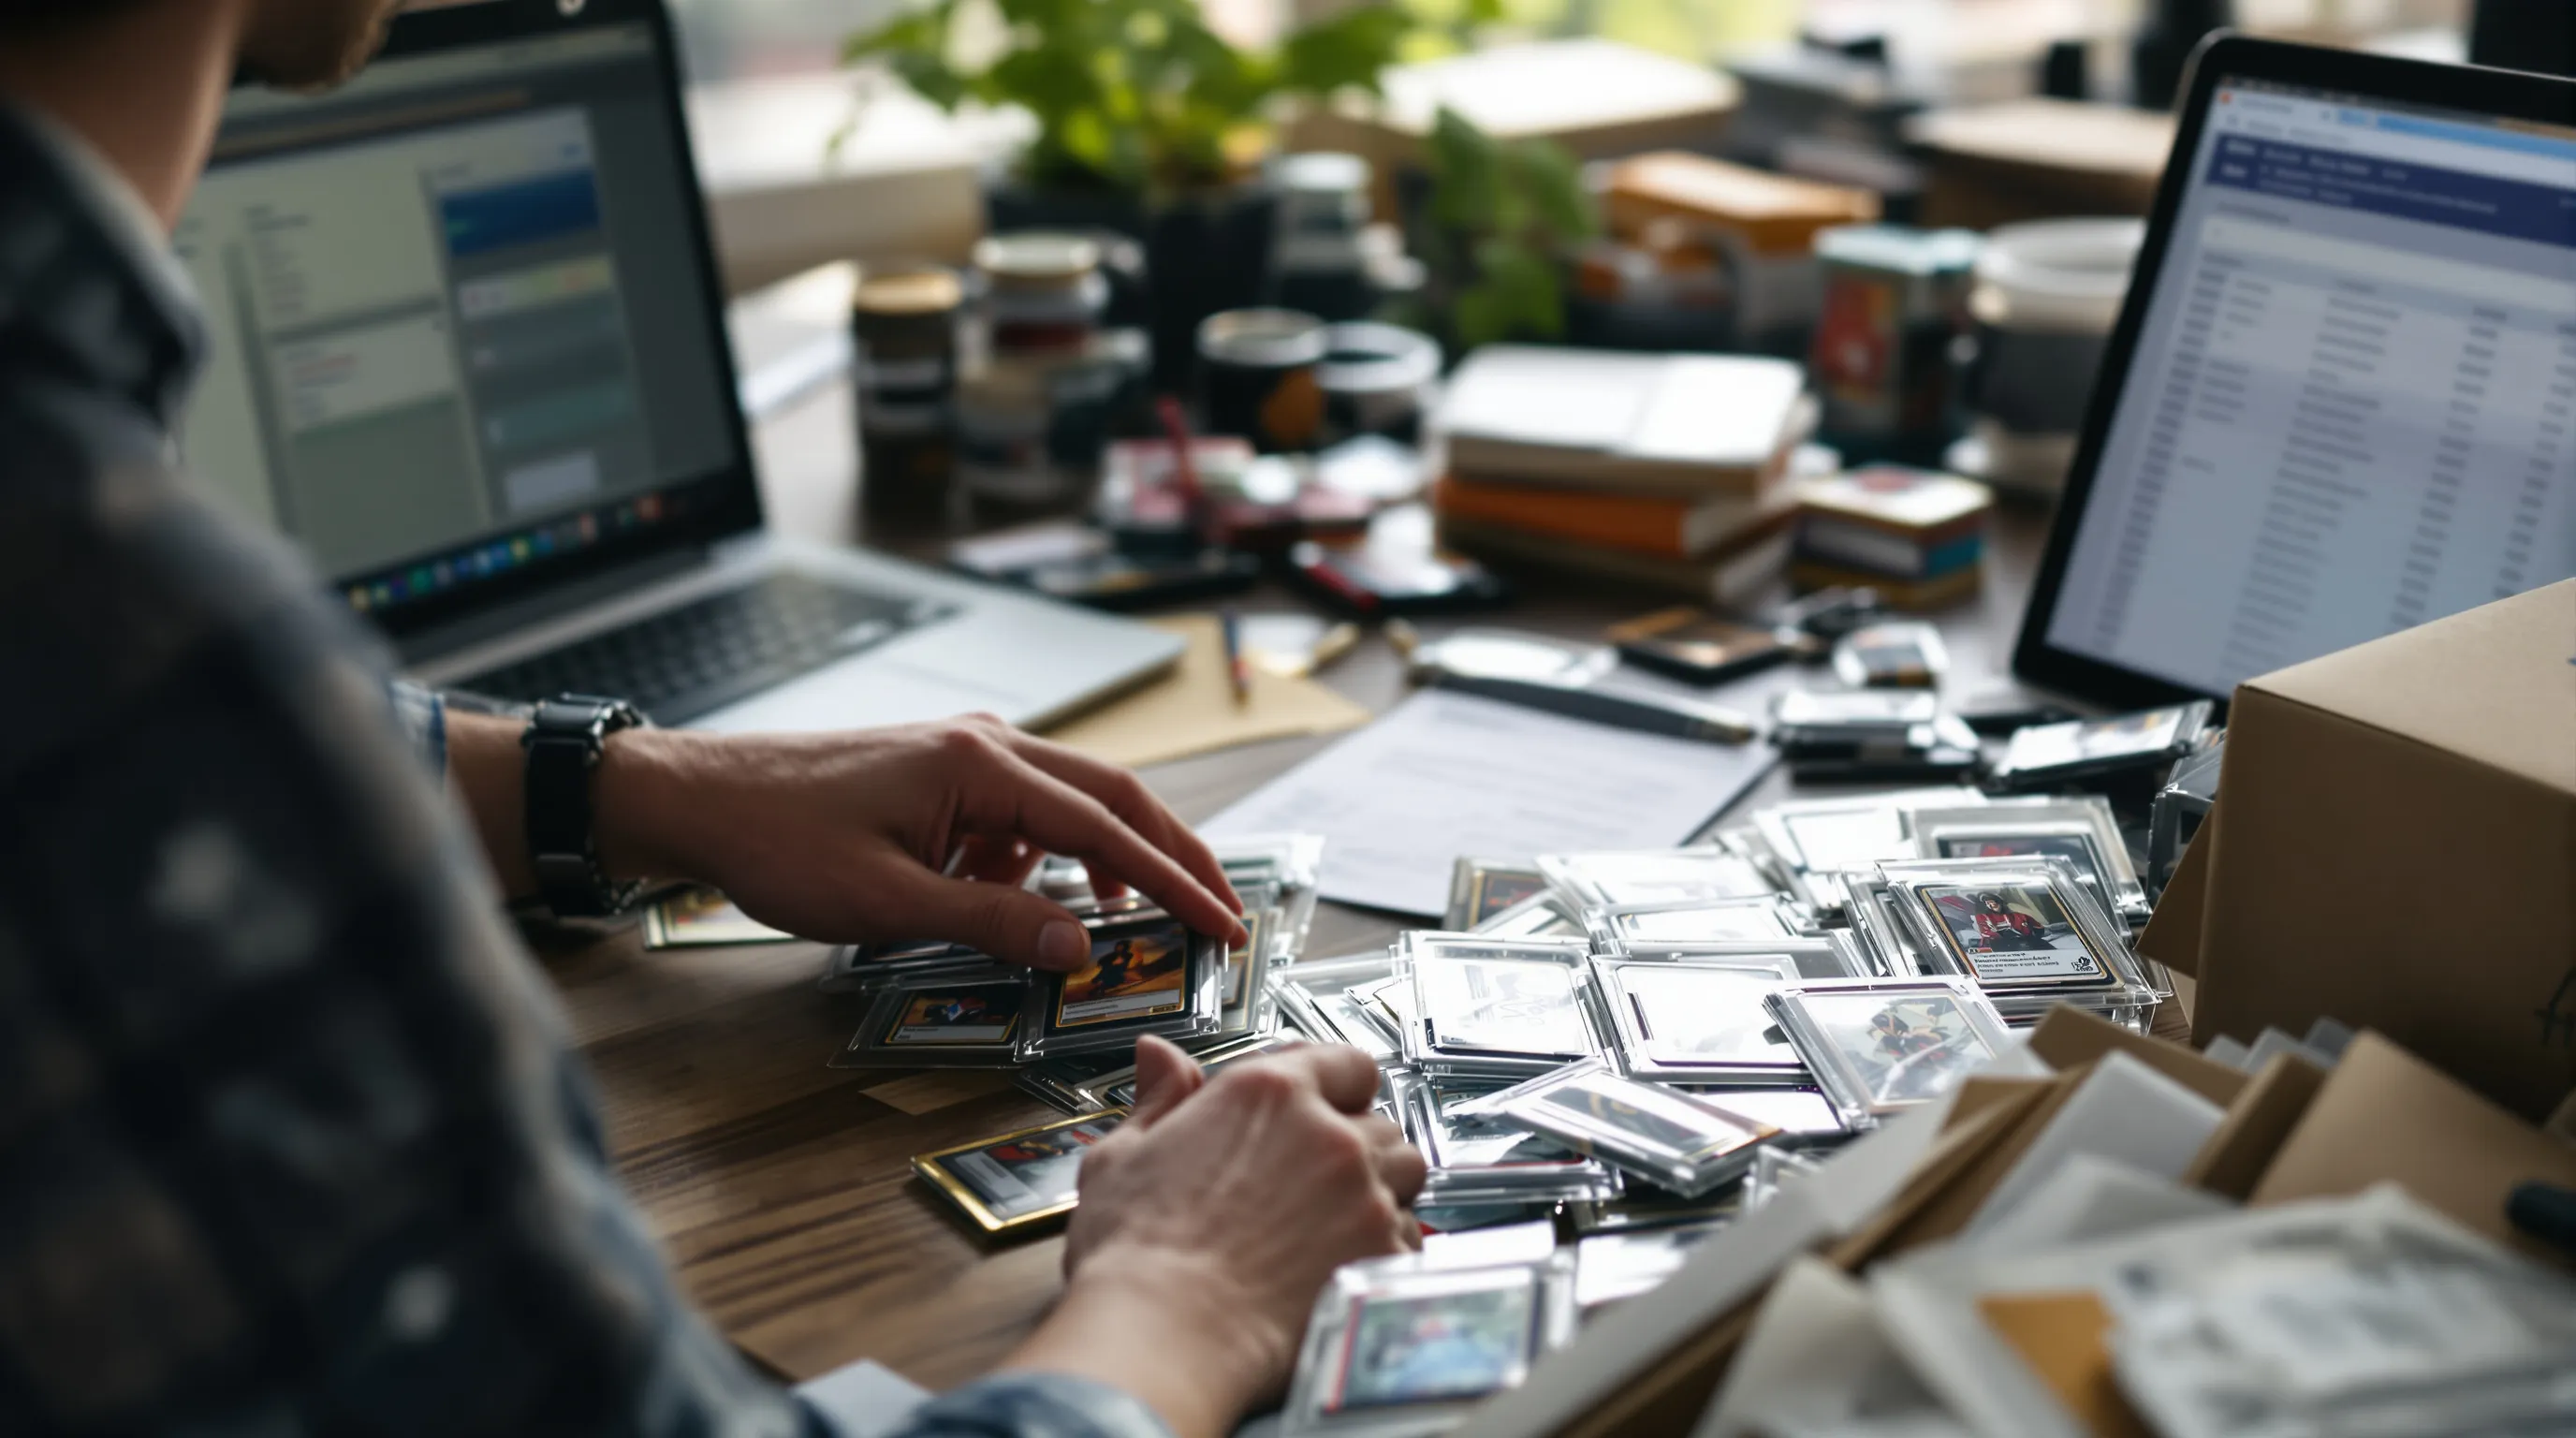
Underwriters look past the cards to the record behind them: balances honored, packs shipped, buybacks paid.
Most rip site owners walk into underwriting expecting one question about time in business. Underwriters ask something narrower. They want to see how the platform has handled the money sitting in the middle of every sale: prepaid credit customers load before they buy, stored balances held on the platform, and buybacks that turn pulled cards back into cash.
Our underwriting team describes rip, mystery-pack and break platforms as a five-part shape, not a trading-card store. Prepaid credit comes first. A randomized outcome follows, since nobody knows which card the pack or break spot will deliver. Then comes delayed physical fulfillment, with cards shipped later or held in a vault. Stored balances and buybacks complete the picture.
That shape is also why a rip site should not apply as a card shop: the label misstates the business an underwriter actually has to price. In my view, the details that carry the most weight are the ones an underwriter can trace from end to end: where cards ship from, who handles them along the way, and the billing descriptor customers see on their statements. Processors that already board platforms like Courtyard or Rips by Triumph have underwritten this shape before, and they know which records to ask for.
Underwriters also open the live site rather than trust screenshots. What they find there has to match the application.
The sections below cover what counts as history for each element, where the available evidence on minimum months runs out, and why approval can still arrive with a reserve attached. It starts with the element applicants most often underexplain: the stored balance a customer can spend, leave idle, or convert through a buyback.
The obvious question for a rip site owner is how many months of history a processor needs before it will board the business. In my view, it is the wrong first question. Underwriters reviewing a rip, mystery-pack, or live break platform are not counting months. They are reading what those months show.
The SeamlessChex underwriting team describes the business an acquirer actually prices as prepaid credit, a randomized outcome, and delayed physical fulfillment, with stored balances and buybacks in the middle. Platforms such as Courtyard, which sells digital packs of vaulted, graded cards, and Rips by Triumph, a mystery-pack app from Triumph TCG, carry that same shape. A processor already comfortable with either has underwritten it before.
So operating history matters in a specific way. Practitioners in high-risk processing say the preparation that matters most happens in the 2-3 weeks before you apply, and that it can speed approval and lower reserve requirements. Practitioners also suggest pairing that record with a growth-oriented business plan, so the projection reads as the next step of a track record rather than a hope.
One more point before going further. Underwriters in this space also weigh supply-side risk almost as heavily as transaction risk, which puts your fulfillment records under the same light as your card statements. For a rip site, that means being ready to explain what happens to a vaulted card between the pull and the moment it ships or is bought back.
What the evidence does show is which records persuade an underwriter, which decline triggers to avoid, and what terms to expect once you are approved.
Questions this article answers
What are underwriters actually pricing when a rip site applies?
Underwriters price five things at once: prepaid credit, a randomized outcome, delayed or vaulted fulfillment, stored balances, and buybacks. The trading cards themselves are almost beside the point.
Before you draft an application, answer five plain questions about how your platform works:
- Does the customer fund a balance before choosing a pack or a break spot?
- Is the card each customer receives unknown at the moment they pay?
- Does the card ship later, or stay in a vault, rather than ship at checkout?
- Does customer money sit on the platform between purchases?
- Do you repurchase pulled cards from customers?
A yes to any of them changes how you will be reviewed. A yes to all five describes the typical rip platform.
Our underwriting team framed it this way in September 2026: the processor "isn't really pricing 'trading cards.'" It is pricing a financial shape. In our team's view, that shape has five elements, and every rip, mystery-pack, and live break business carries some version of each:
- Prepaid credit: the customer funds a balance before buying anything.
- Randomized outcome: the pack or break spot delivers a card nobody can name in advance.
- Delayed physical fulfillment: the card ships later or stays vaulted on the customer's behalf.
- Stored balances: customer money is held on the platform, sometimes for weeks.
- Buybacks: the platform repurchases pulled cards, which creates a cash-out path.
The common assumption is that a rip site gets underwritten like a collectibles retailer with unusual packaging. It does not. An operator who applies as a "card shop" misdescribes the business, and an underwriter who later sees balances and buybacks on the live site will treat that gap as a red flag.
Why does the shape matter more than the product? Because each element points to a different way money can go wrong. As I read it, prepaid credit and stored balances raise future-delivery and refund exposure. The randomized outcome invites a classification question and chargeback exposure. Delayed fulfillment invites non-receipt disputes. Buybacks draw money-movement and cash-out review, because value can flow back out of the platform.
A commenter in an April 2026 r/PaymentProcessing thread on high-risk boarding captured the underwriter's real question: it is less about whether you have a business and more about "will this cause issues or losses?" That framing fits rip sites exactly. Combining 2 sources points to the same conclusion: the application has to describe the shape, then show how each element is controlled.
That is a higher bar than a standard ecommerce review. It is also a clearer one. Once you know which five things are being priced, you know what your records need to prove.
For operators weighing their options, a dedicated high-risk credit card processing relationship is built for exactly this kind of review. The qualification question for any processor is simple. Has it boarded businesses with this shape before?
In short, the underwriter is not asking what you sell. It is asking how you hold, deliver, and return customer value.
What counts as operating history for a rip or break platform?
Operating history is the record of how your business behaved with real customer money. For a rip site, underwriters read it for proof that balances, fulfillment, and buybacks stayed under control.
Age alone proves little. A platform that has run for years with messy refunds tells an underwriter less than one with a short, clean record. What the reviewer wants is behavior: deposits that match the story, disputes handled quickly, and customer value that moves the way the application says it does.
Practitioners in an April 2026 r/PaymentProcessing discussion of high-risk boarding were blunt about the downside. One commenter named "no business history" among the biggest instant-decline issues they had seen. Another listed "no history with aggressive projections" as a decline trigger. Those are not the same warning. The second suggests a thin record is survivable when the volume you project is realistic, and fatal when it is not.
The same thread offered the most practical advice on the subject: "If you have any processing history at all, even from a non-high-risk site or a previous business, get those statements ready. 3 months of clean data beats every other application asset."
For a rip or break operator, that opens up more sources of history than most expect:
- Statements from the current platform, including months processed through an aggregator before you applied for a dedicated account.
- Statements from a previous business run by the same owners, even in a lower-risk category.
- Operational records behind the statements, such as a balance ledger, a buyback log, and shipping or vault records, which in my view give the numbers their meaning.
Statements show volume. They do not show control. A clean month for a rip site is one where an underwriter can trace prepaid balances to packs opened, packs opened to cards shipped or vaulted, and buybacks to a stated pricing policy. Our underwriting team's guidance is that the application should describe the business shape and how each element is controlled, and history is the evidence that the controls are real rather than promised.
I won't put a month count on each element here. The underwriting view our team shared names the five elements, not a minimum duration for each, and any fixed number would be a guess. My advice is to keep your buyback ledger right beside your card statements, since a buyback is a cash-out path and an underwriter will want to trace each payout.
There is also a floor. SeamlessChex works with established businesses processing at least $25,000 per month, so a platform still testing demand is better served building its record first. Once that record exists, a review of dedicated merchant services for established businesses is the natural next step.
The catch is that clean history gets you in the door. It does not settle every term an acquirer sets once you are inside, and the first months after approval are where a rip operator can feel the squeeze on buyback cash.
How many clean months does a rip site need before an underwriter says yes?
Ask people who coach high-risk applicants what convinces an underwriter, and the same answer keeps coming back. The number of months involved is smaller than most rip site owners would guess.
In an April 2026 thread on Reddit's r/PaymentProcessing, a commenter advising sellers in a high-risk category was blunt: "3 months of clean data beats every other application asset." Those statements can come from any earlier processing, the commenter added, "even from a non-high-risk site or a previous business." The thread was about research-use peptide sellers. The same commenter said, "None of this is peptide-specific. It's high-risk hygiene generally." Three months is a practitioner's rule of thumb. No underwriter has published it as a standard.
Why would a short record count for more than a confident forecast? A forecast with no record behind it is a warning sign in its own right. A second commenter in the thread listed "no history with aggressive projections" as a reason for decline. A third went further and named "no business history" alone as a cause of instant decline. The two disagree on whether being new is fatal by itself. Both agree that big projected volume can't replace months of evidence, and that a large projection on a thin record makes the application look worse.
For a rip site, the word "clean" carries extra weight. Our underwriting team's view is that a processor reviewing a rip or break platform "isn't really pricing 'trading cards'." The processor is pricing prepaid credit, a randomized outcome and delayed physical fulfillment, "with stored balances and buybacks in the middle." Three months of tidy card sales prove little if the statements say nothing about how balances, vaulted cards and buybacks actually behaved.
| Element our underwriters price | What it means | The question your clean months should answer |
|---|---|---|
| Prepaid credit | The customer funds a balance before buying | Did the money customers paid in turn into purchases or refunds as promised? |
| Randomized outcome | The pack or break spot delivers an unknown card | Did customers know exactly what they were buying, and did disputes stay low? |
| Delayed fulfillment | The card ships later or stays vaulted | Did cards ship, or stay in the vault, the way the site said they would? |
| Stored balances | Customer money held on the platform | Can you account for the balances held on the platform in every month? |
| Buybacks | The platform repurchases pulled cards | Were buybacks paid as offered? |
Underwriters also compare the record with what they can see for themselves. "Underwriters check the live site, not the screenshots you send," the peptide-thread commenter wrote, and any gap between the application and the visible site "will get flagged." Picture a rip site whose history is filed as an ordinary card shop while its live pages offer buybacks and vaulted inventory. That is the kind of gap the commenter describes.
What practitioners treat as a clean month
- Chargebacks stay below about 1%. Two commenters said, independently of each other, that risk starts around that level.
- Refund, terms and privacy pages are live. "Underwriters click the footer links."
- The live site matches the application.
- Disputes get answered within 48 hours, using templates written in advance.
Practitioner guidance from an April 2026 r/PaymentProcessing thread about another high-risk category.
History has two important limits. First, it doesn't lower our floor. We require at least $25,000 in monthly processing volume, and we work with established businesses, so a platform that has not launched yet falls outside what we board. Clean months show control. Volume decides whether an application gets considered at all.
Second, clean months don't guarantee good terms. In February 2026, a new merchant in an undisclosed high-risk industry wrote on r/smallbusiness about asking for a waiver on a 10% rolling reserve held for six months. The merchant cited good credit and no chargeback history. The processor answered that the reserve was "non negotiable for new merchants in my industry." That is one merchant's account, and the reserve section below goes further. It still shows that a clean record and a new account can lead to two separate decisions.
So what is the history for? Projections can't show whether customer money behaved, and the months can. Volume gets a rip site considered, and the history shows whether the five moving parts held up. Being new in a high-risk category can still affect the terms after approval.
- Gather statements from any earlier processing, including a previous business or a non-high-risk site, and pull together your most recent three months.
- Go through those months element by element and confirm the records show balances honored, cards shipped or vaulted as promised, and buybacks paid.
- Base your projected volume on what the statements already show, and leave hoped-for growth to a separate plan.
- Compare each month's chargebacks with the roughly 1% line practitioners describe, and set up a written dispute process before you apply.
- Ask every processor, us included, whether your clean months have to meet its volume minimum, and whether new merchants in your category get a reserve, before you sign anything.
How we checked this
We used two public Reddit threads from 2026 and our own underwriting and qualification guidelines. The five-part description of rip sites, the $25,000 monthly minimum and the rule that we work with established businesses are SeamlessChex figures and positions, shared by our team in July and September 2026. The three-month figure, the 1% benchmark and the 48-hour response come from anonymous commenters in a thread about peptide sellers, so none of them is specific to rip sites. The reserve account comes from one merchant who did not name their industry. We board rip and break platforms, so we have a stake in this answer. We still don't know whether underwriters across the market apply a fixed month count to rip sites, or whether clean months must reach a processor's volume minimum to count.
- r/PaymentProcessing, thread on payment processing for high-risk sellers, April 29, 2026.
- r/smallbusiness, thread on a merchant account reserve hold, February 17, 2026.
- SeamlessChex underwriting team, view on how card rip, mystery-pack and break merchants are priced, September 4, 2026.
- SeamlessChex merchant qualification guidelines, provided by Evan Albert, July 2026.
Why can a rip site with clean history still face a reserve after approval?
Approval and account terms are separate decisions. A new merchant in a high-risk category can still be boarded under a rolling reserve, and strong personal credit may not change that.
A February 2026 post on r/smallbusiness shows how this plays out. A newly approved merchant in a category processors label high risk found a clause holding 10% of all sales for the first six months as a "rolling reserve" for risk management. On $10k in monthly sales, $9k was deposited and $1k was held. After six months, roughly $6k sat with the processor before it started releasing the money slowly.
The merchant asked for a waiver. They cited good credit and no chargeback history. The processor's answer was that the reserve is "non negotiable for new merchants in my industry."
Contrary to what many owners expect, a clean credit file did not move the processor at all. The deciding factors were the category and the fact that the account was new. The poster never named their industry, so this was not necessarily a rip site. It does show the default posture toward new high-risk accounts, and rip platforms sit squarely in that group.
Two more details from that thread deserve attention. The contract ran to about 40 pages, and the merchant did not notice the reserve clause until after signing and processing. Their accountant's advice came too late: reserves are common for new merchant accounts and should be negotiated before you sign.
Here is why a reserve bites harder on a rip site than on most stores. Your incoming card revenue funds new inventory and pays for buybacks. When a slice of every sale is held back, the cash you planned for repurchasing pulled cards shrinks first. A platform that promises fast buybacks and then slows them because of a reserve it did not plan for creates exactly the customer friction underwriters worry about.
That loop is worth stating plainly. Prepaid balances and buybacks are money the platform may owe customers later. A reserve is the acquirer's cushion against that same obligation.
Clean history also does not end scrutiny after boarding. Practitioners in high-risk processing put the chargeback danger zone at about 1%, where an account starts drawing attention and, if things worsen, can be lost. They describe early reserves as the processor protecting itself against chargebacks while the account proves itself.
So what should you do with this? Three practical steps help:
- Read the reserve clause, its percentage, its duration, and its release schedule before you sign.
- Build the held amount into launch cash flow, with buyback liquidity funded separately.
- Ask the processor what record, over what period, would justify reviewing the reserve.
Payout design is part of that conversation too. One option worth raising is paying buybacks out through a bank rail such as Seamless ACH payments, while customers keep paying by card, so the two flows stay easy for an underwriter to trace.
Shopping around may not remove it either: the same poster said other processors they checked had similar reserve requirements for businesses classified as high risk. That makes a reserve the price of being new, and the next question is how quickly your records can make you look established.
What should a rip site owner do next to get boarded?
Document clean months showing balances honored, cards delivered, and buybacks paid. Then apply to a processor that already boards rip platforms, and describe your real shape.
High-risk ecommerce operators keep asking which credit card processing is best for a business like theirs. For rip sites, I think the deciding question sits underneath that one. Can your records prove control of prepaid credit, randomized outcomes, delayed fulfillment, stored balances, and buybacks?
Before you apply, click every footer link yourself, because practitioners warn that a refund, terms or privacy page that returns a 404 or redirects can end the review. A reserve calculated against your first months makes the cost of thin history concrete, and it falls hardest on the cash you set aside for buybacks.
My advice is simple. Start keeping a balance ledger and a buyback log now, before you apply. Match them to your statements month by month. Then choose a processor whose underwriters already know platforms like Courtyard and Rips by Triumph, so your application is read as the business it is rather than as a card shop with unusual habits.
Frequently Asked Questions
What else do rip site owners ask about operating history and approval?
Most follow-up questions come back to the same point: underwriters want proof that customer balances, deliveries, and buybacks are controlled, and records showing that carry more weight than volume.
How many months of operating history does a rip site need?
No published standard sets a fixed count for each element. What persuades an underwriter is clean months showing balances honored, cards delivered or vaulted, and buybacks paid. Prior statements from a previous business can count too.
Do stored balances make a rip site harder to approve?
They add review, not an automatic decline. A stored balance is customer money held on the platform before it is spent, so it creates refund and future-delivery exposure. A clean balance ledger answers that concern directly.
Are buybacks treated as a cash-out risk?
Yes, in my reading they draw money-movement review. A buyback is the platform repurchasing a pulled card, which lets value leave the platform. Document your pricing policy and how payouts are made.
Will an underwriter classify my rip site as gambling?
The randomized outcome is what raises that question. Describe exactly what each pack or break spot contains and how it ships. An accurate description of your real business shape is the strongest answer you can give.
How quickly can SeamlessChex onboard a rip platform?
SeamlessChex offers same-day onboarding and no contracts for established businesses, subject to underwriting review. Start at seamlesschex.com/contact with your recent statements ready.
Can live break sellers accept cards in person as well as online?
Yes. SeamlessChex supports credit card and ACH payments online or in person, so a seller running live breaks and an online storefront can keep both under one relationship.
Written by
Jonathan Albert
Co-Founder, SeamlessChex
Jonathan Albert is Co-Founder of SeamlessChex, a credit card processing and fintech payments platform recognized on the Inc. 5000.
Connect on LinkedInSeamlessChex works with established businesses processing a minimum of $25,000 per month.