

Quick Answer
A breaker leaving Whatnot or Fanatics Live needs the same credit card merchant account as a vaulted-rip site, underwritten on prepaid credit, randomized outcomes, delayed fulfillment, stored balances and buybacks.
Key Points
- SeamlessChex underwriters price card breaks on five elements: prepaid credit, randomized outcome, delayed fulfillment, stored balances and buybacks, the same shape as vaulted-rip platforms like Courtyard.
- The Athletic reported CardsHQ's live-selling and breaking business hit $15 million in 2025 and is estimated to top $30 million in 2026, largely on Whatnot and Fanatics Live.
- SeamlessChex works with established businesses processing at least $25,000 a month and offers same-day onboarding with no contracts.
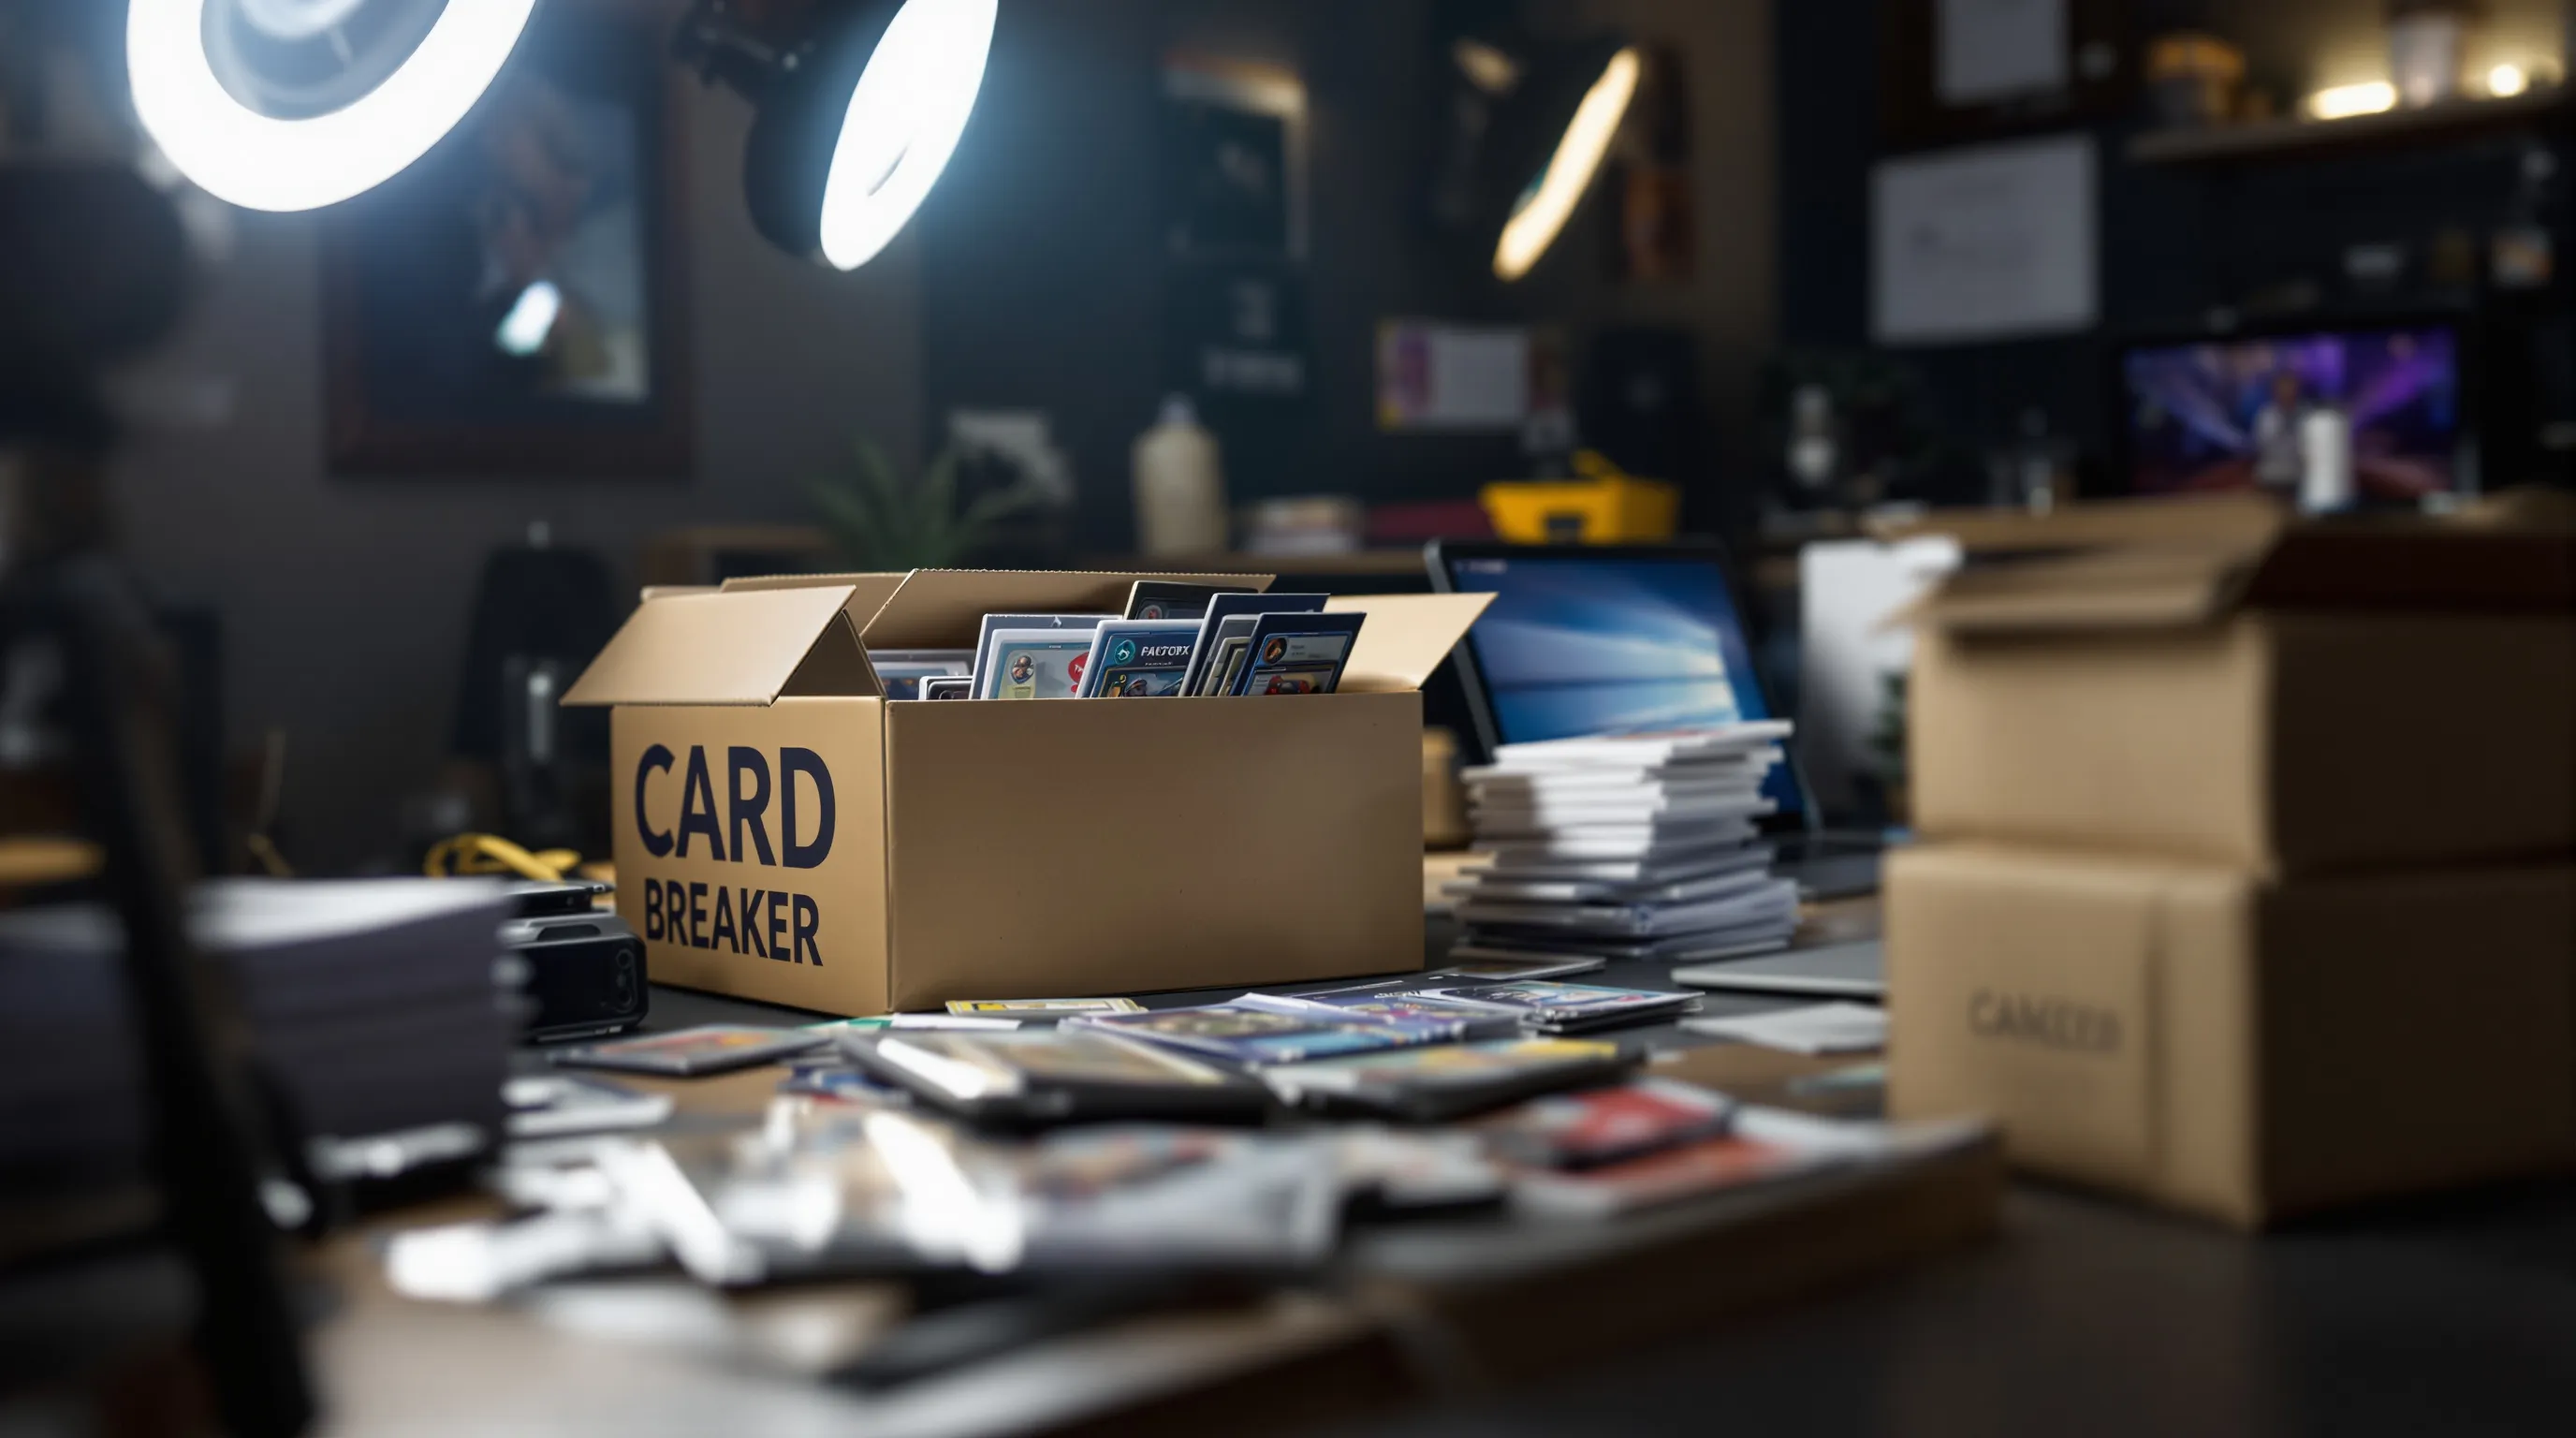
A live break: prepaid spots, an unknown pull, and cards that ship later.
Live breakers already sell the five things an underwriter prices: prepaid credit, a randomized outcome, delayed fulfillment, stored balances and buybacks. Before you apply, ask which of those five your own checkout will carry. The research section below walks through what changes when you leave.
Marketplaces carry the trust for you. On a July 2024 episode of the You Can't Comp This card podcast, the hosts read out a Fanatics Collect statement ending sales of autograph-only authenticated cards after a fake card sold there. Ask what record you would show a processor if a buyer disputed a spot tomorrow. Your application has to show it.
Do live break sellers need their own merchant account? Once they sell on their own checkout, yes. And the account they need looks exactly like a vaulted-rip site's.
The timing matters. Live breaking is no longer a side business run on someone else's app. Sellers told The Athletic the biggest live-selling card businesses now generate $100 million or more a year. Money at that scale tends to leave the marketplace eventually, and underwriting is where it lands first.
What does an underwriter see in a live card break?
An underwriter sees prepaid credit, a randomized outcome, delayed fulfillment, stored balances and buybacks. Our underwriting team prices those five elements, not the trading cards themselves.
Before you apply anywhere, run your own breaks through five plain questions:
- Prepaid credit: does the buyer pay for a spot before the box is opened?
- Randomized outcome: does a wheel spin, random team or random division decide what they get?
- Delayed fulfillment: do pulled cards ship days after the stream ends?
- Stored balances: do you hold credits or unshipped hits on a buyer's behalf?
- Buybacks: do you offer to buy pulls back for cash or credit?
Most break formats answer yes to the first three on their own. Random team and random division breaks are random by design. Pick your team breaks still leave the cards inside each slot to chance. Case breaks and hit drafts widen the gap between payment and delivery, because hits are pulled first and shipped later. In 2025, one breaker's own pricing put high-end hockey spots at $100 to $500+ per spot, which is a lot of prepaid money waiting on a mailbox.
If your format adds credits or buybacks, expect the underwriter to ask how you control each one. Card apps that sell digital packs face the same five questions. An analysis of 4 sources shows one pattern. The research section below walks through what that pattern means for your application.
The common assumption is that a breaker is a card shop with a camera. It is not. In my reading of our underwriting team's notes, any processor already comfortable with Courtyard or Triumph has underwritten this shape before. A retail-style merchant payment processing solution priced for hobby stores misses all five elements, which is exactly where a breaker who walks off the platform starts getting declined.
Does a breaker leaving Whatnot or Fanatics Live need its own merchant account?
Fanatics is hiring an engineering lead whose new team should help Fanatics Live sellers "get paid on time, with full clarity on what they earned." Leave the platform, and that job is yours.
On a platform, payment work happens out of sight. Investor Jason Stoffer profiled Whatnot in January 2026 and described an app that handles bids, payments and shipping for sellers and gives buyers customer support and authenticity guarantees. Sell spots on your own site and that layer is gone. So the first answer is yes: an established breaker taking cards directly needs its own merchant account.
Which account depends on what the break sells. CardChasers MTL, a Quebec shop that says it has hosted "thousands of live breaks on Whatnot," explains the format: collectors pay for a spot, a wheel spin or random draw assigns teams, and cards ship afterward with tracking. Our underwriting team says a processor "isn't really pricing 'trading cards.'" Three of the five elements it does price come with every break.
| Underwriting element | On your own checkout | What brings it in |
|---|---|---|
| Prepaid credit | Always | Buyer pays before the box is opened |
| Randomized outcome | Always | Wheel spin, random draw, luck of the box |
| Delayed physical fulfillment | Always | Cards ship after the show |
| Stored balances | Only by choice | Holding buyer funds between shows |
| Buybacks | Only by choice | Repurchasing pulled cards |
Our team describes rip platforms the same way, "with stored balances and buybacks in the middle." A breaker who adds either of the last two rows hands an underwriter that file. One who adds neither still carries three rows where a buyer pays first and learns later what arrived.
Disputes come from those three rows. eBay limited case, box and pack breaks to pre-approved sellers from July 18, 2023, and Cardlines editor Shaiel Ben-Ephraim saw cutting dispute costs as one likely reason. A Blowout Forums user named Dukefett put the practical problem plainly: "eBay doesn't take video as evidence for any disputes."
The Athletic reported in June 2026 that platform problems range from wrong items to "the use of sleight-of-hand to swap high-value cards in a pack for less desirable ones," and Cardlines noted that some buyers exploit buyer protections to cheat breakers. On a platform, a trust operation absorbs those claims.
1 in 3
Whatnot says one in three of its employees works on buyer and seller trust and that it bans tens of thousands of accounts every week. These are company figures, reported by The Athletic in June 2026.
Plenty of breakers are big enough to move. Several popular live sellers estimated to The Athletic that the biggest live-selling businesses in cards earn $100 million or more a year.
Read the bars with care. The 2026 figures are founders' estimates, earned mostly on the platforms. Mike Gioseffi of Sports Cards Nonsense said his business could shift to a near even split between Fanatics Live and eBay Live by year end. What counts for an account is the share that would run through your own checkout.
Another pressure comes from gaming. Dustin Gouker, who writes about the gambling industry, reported that Underdog launched digital rips in September 2026, that PrizePicks followed in October, and that several sweepstakes sportsbooks and casinos already offer them. Breaks themselves still lack a settled category: "There are no clear federal laws regarding breaks," Cardlines wrote in 2023. A breaker should be ready to explain in its own words how a spot is sold.
Leaving the platform does not change the break's risk. Prepaid spots, chance and later shipping travel with the breaker. What moves is the name on the account when a buyer disputes a spot, plus the payouts, support and trust staff that once absorbed that exposure. Whether your file matches a vaulted rip site's comes down to two choices: buyer credit and buybacks. Calling yourself a card shop does not change the rest.
- Check the five elements one by one and state plainly whether you hold buyer credit between shows or buy back pulled cards.
- List what the platform handles now, from payments and payouts to buyer support, and decide who covers each job on your own checkout.
- Ask any processor, us included, what evidence it can submit when a buyer says a spot was not as described, and whether stream video helps.
- Estimate how much volume would actually move to your own checkout before comparing it with any processor's minimum.
- Write a plain description of how a spot is sold and teams are assigned, so you can answer classification questions yourself.
How we checked this
We used news reporting from The Athletic, a 2023 Cardlines analysis that quotes a hobby forum user, an undated Fanatics job posting, an investor's profile of Whatnot, a breaker's explainer for buyers, and a gaming industry newsletter. The five-element framework (September 2026) and the $25,000 monthly minimum (July 2026) come from our own underwriting team. The revenue figures are founders' reports and estimates covering several platforms. Whatnot's trust figures are the company's own. The video point comes from one forum user and describes eBay's practice in 2023. CardChasers MTL promotes its own breaks. We underwrite breakers and rip platforms and want their business, so we have a stake in this answer. Still unknown: how often breaks draw chargebacks once they leave a platform. None of our sources measured that.
- The Athletic, report on sports card breaking across Whatnot, Fanatics Live and eBay, June 10, 2026.
- Cardlines, analysis of eBay's card breaks policy, July 5, 2023.
- Fanatics, Fanatics Live engineering lead job posting, undated.
- Jason Stoffer, investor profile of Whatnot live shopping, January 22, 2026.
- CardChasers MTL, explainer on how card breakers work, January 29, 2025.
- Dustin Gouker, newsletter report on PrizePicks launching digital rips, October 14, 2026.
- SeamlessChex underwriting team, card rip and break underwriting perspective, September 2026, and merchant qualification minimum, July 2026.
Which merchant account providers approve mystery box or card rip websites?
Providers that approve them already underwrite prepaid, randomized-outcome merchants. Many general processors decline, because breaks sit in an unsettled legal category where disputes are hard to prove.
The legal question has not gone away. Cardlines wrote in 2023 that there were no clear federal laws on breaks, and that nobody was sure whether to classify them as entertainment or as a raffle. That is the reader's question to answer with counsel, not one a processor settles for you. Still, it shapes every risk review.
Platforms felt the same pressure. In 2023, eBay told sellers that only pre-approved sellers could run case, box and pack breaks, effective July 18, 2023, with no published application method. Dispute evidence was the other sore point: a Blowout Forums user noted at the time that eBay did not accept video in disputes. A buyer claiming a missing hit from an hour-long stream is hard to answer without it.
Now add the newest twist. Dustin Gouker reports that several sweepstakes sportsbooks and casinos already offer digital rips, "and more are coming." I'd expect underwriters to read that as a signal. Breaks and rips are being sold next to gaming-adjacent products, so they will be compared with them.
Contract terms follow the risk. In high-risk accounts, personal guarantees are common, though practitioners describe them as negotiable with reserves, capped liability or strong financials. A prior processor closure raises the bar further, and a breaker in that spot should read up on TMF/MATCH list merchant account approval before applying, since the next underwriter will see the same file.
How do card break businesses accept credit card payments outside Whatnot or Fanatics Live?
They open a dedicated credit card merchant account underwritten on the break's real risk shape. Approval starts with an established operating history and at least $25,000 in monthly processing volume.
On a marketplace, the platform owns the payment relationship. A Fanatics job posting for its Live Breaking unit says the new team will have "full ownership of the creator and seller experience," including third-party payment providers, and lists a seller goal to "get paid on time, with full clarity on what they earned." That is a helpful promise. It is also a reminder that payout timing is set by someone else.
Scale changes the math. The Athletic reported that CardsHQ's live-selling and breaking business hit $15 million in 2025 and is estimated to top $30 million in 2026, largely on Whatnot and Fanatics Live. At that size, one platform's payout rules are a real concentration risk.
Here is how I'd approach the move:
- Describe the five elements, not a card shop. Spell out how you take prepaid spots, randomize outcomes, ship later, hold balances and handle buybacks.
- Pick a processor that has already boarded rip and mystery-pack platforms. A team that knows vaulted-rip models will recognize your file.
- Lead with card acceptance. Credit card processing carries the checkout; buyers pay the way they already do on stream.
- Add bank payments second. Accepting ACH payments can fund larger balances and pay out buybacks alongside your card rail.
One gap worth naming: there is no public approval data comparing live sellers with vaulted-rip sites. If you add bank payments for balances or buybacks, Nacha reports Same Day ACH carried 1.4 billion payments worth $3.9 trillion in 2025, so the rail can handle the volume.
Where is break processing headed next?
Live breaks and vaulted rips are heading toward one underwriting file. Breakers who apply on that basis now will be ready when platform payout rules shift again.
The volume is already there. The Athletic, citing research firm eMarketer, reported that U.S. social commerce grew an estimated 21.5 percent to more than $87 billion in 2025, with trading cards and other collectibles a significant piece of that total. Platforms will keep tightening who may run breaks.
My advice is simple. Lead with card acceptance, and keep bank payments ready as the second rail: Nacha reports Same Day ACH volume rose 16.7% in 2025. Then the only open question is which processor has seen your shape before, and that is a short list worth calling this quarter.
Frequently Asked Questions
What else do live breakers ask about their own merchant account?
Most questions come down to three things: how to describe the break, why disputes worry processors, and how quickly an established breaker can start taking card payments directly.
Should I apply as a trading card shop?
No. A card shop sells a known item. A break sells a prepaid spot with a randomized pull, shipped later, sometimes with stored balances and a buyback, meaning the seller repurchases a pulled card. I'd describe each of those and how you control it. Whether a break counts as a game of chance is a question for your own counsel; the application just needs to be accurate.
Why do processors care so much about break disputes?
Delayed fulfillment invites non-receipt claims. Back in 2023, Cardlines quoted a collector forum user who expected breaks to be "huge issues for 'item not as described' returns." Clear spot records and shipping proof answer those claims.
How fast can an established breaker get set up?
We offer same-day onboarding with no contracts. Start through the SeamlessChex contact page, and have your break records ready for underwriting.
Written by
Lily Flanigan
Operations Manager, SeamlessChex
Lily Flanigan is Operations Manager at SeamlessChex, a credit card processing and fintech payments platform recognized on the Inc. 5000, where she focuses on operations and process optimization.
Connect on LinkedInSeamlessChex works with established businesses processing a minimum of $25,000 per month.